Emergency fund strategies for financial peace
Anúncios
Emergency fund strategies involve saving three to six months’ worth of living expenses in accessible accounts like high-yield savings or money market accounts to ensure financial security for unexpected situations.
Emergency fund strategies are essential for ensuring you have a financial safety net in times of need. Have you ever considered how unexpected expenses might impact your budget? Let’s dive into effective ways to build this crucial fund.
Anúncios
Understanding emergency funds and their importance
Understanding emergency funds is crucial for maintaining financial security. These funds act as a safety net during unexpected situations like job loss or sudden medical expenses. Having an emergency fund allows you to tackle life’s surprises without falling into debt.
What is an Emergency Fund?
An emergency fund is a specific savings account set aside for financial emergencies. This could be anything from car repairs to unexpected medical bills. The key is to keep this fund separate from your regular savings to avoid using it for non-emergencies.
Anúncios
Importance of an Emergency Fund
Building an emergency fund is not just about saving money; it’s about peace of mind. Here are a few reasons why having an emergency fund is essential:
- Provides financial security during tough times.
- Reduces reliance on credit cards or loans.
- Helps maintain your standard of living if your income drops.
Creating this fund should be one of your top financial goals. Start by determining how much you realistically need. A good rule of thumb is to aim for three to six months’ worth of living expenses. This may seem daunting, but breaking it down into smaller, manageable goals can help make it achievable.
Once you’ve set a target, try to contribute regularly, even if it’s a small amount. Consider automating your savings to make the process easier. This way, you can build your emergency fund without overthinking it. Remember, every little bit counts and can add up over time.
As your fund grows, keep it in a place where it’s easily accessible but not too easy to dip into for everyday expenses. A high-yield savings account is often a great choice, as it allows your money to earn interest while remaining available for emergencies.
In summary, understanding the importance of emergency funds can empower you to take control of your financial future. By building this safety net, you’re investing in your peace of mind and stability during uncertain times.
How much should you save for an emergency fund?
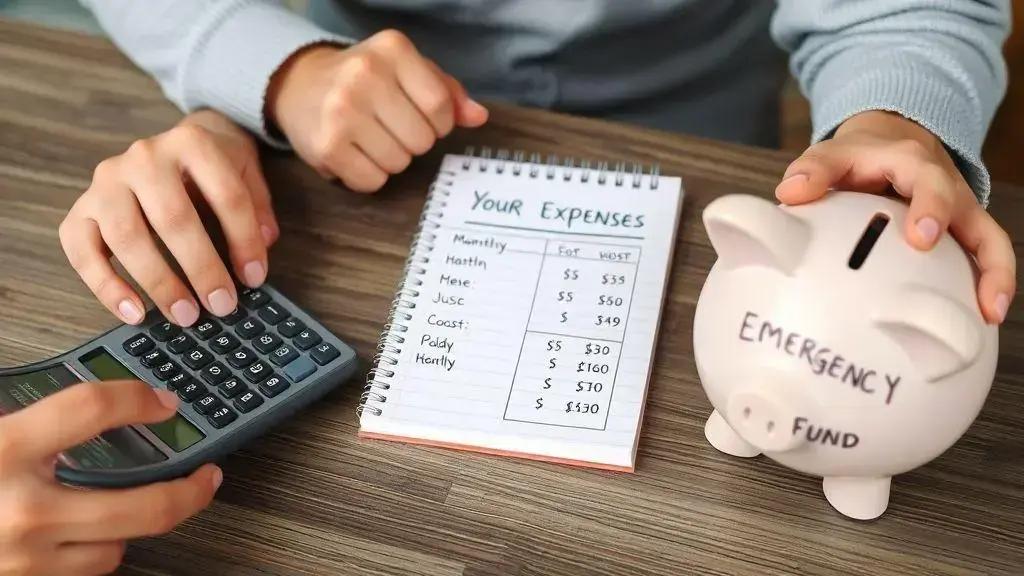
Determining how much you should save for an emergency fund is a crucial step in your financial planning. It’s important to establish a target that reflects your unique needs and lifestyle. Start by assessing your monthly expenses, including rent or mortgage, utilities, groceries, and other necessities.
Calculating Your Target Amount
A good guideline is to aim for three to six months’ worth of living expenses. Here are some factors to consider when calculating your target:
- Consider your regular monthly bills.
- Add any debt payments you make each month.
- Don’t forget about variable expenses like groceries and transportation.
It’s beneficial to write down all your expenses to get a clear picture. Once you have this total, multiply it by three or six, depending on your comfort level with risk. For example, if your monthly expenses are $2,000, an emergency fund of $6,000 to $12,000 would be advisable.
Factors to Adjust Your Savings Goal
Several factors can impact your ideal emergency fund amount:
- Your job stability: If you’re in a field with a high turnover rate, consider saving more.
- Your health: If you have ongoing health issues, factor in those costs.
- Dependents: More dependents may mean higher living costs.
Sometimes, starting small is the best approach. You don’t have to reach your goal overnight. Building your fund incrementally can relieve some pressure. Focus on setting aside a small amount regularly, gradually working up until you meet your target.
Additionally, reassess your emergency fund needs occasionally. If your situation changes, like a new job or a significant life event, it may be necessary to adjust your savings goal accordingly. Keeping your fund updated ensures it serves its purpose effectively, giving you peace of mind.
Best places to keep your emergency fund
Knowing the best places to keep your emergency fund is vital for maximizing the benefits of your savings. You want to choose a safe and accessible option that also allows your money to grow. Here are some effective places to consider.
High-Yield Savings Accounts
Many people find that a high-yield savings account is an excellent choice for their emergency fund. These accounts offer better interest rates compared to traditional savings accounts, allowing your money to grow more effectively.
Money Market Accounts
Another great option is a money market account. These accounts often provide higher interest rates than standard savings accounts and come with check-writing privileges, which can be helpful in emergencies.
- Usually have higher minimum balance requirements.
- Allow easier access to your funds.
- Often offer competitive interest rates.
Both high-yield savings accounts and money market accounts are relatively low-risk, making them suitable for an emergency fund. It’s important to choose a bank with a good reputation and insurance from the Federal Deposit Insurance Corporation (FDIC) to protect your savings.
Certificates of Deposit (CDs)
Certificates of Deposit (CDs) can be a good option if you’re willing to let your money sit for a specific period. CDs usually offer higher interest rates compared to savings accounts but require you to commit your funds for a set term.
Keep in mind that accessing your money before the CD matures may result in penalties. Therefore, it might be wise to use CDs for a portion of your emergency fund rather than the entirety.
Ultimately, the best place for your emergency fund depends on your individual needs. Consider factors like accessibility, interest rates, and how quickly you might need to access the funds. Assess your options and choose the one that provides security while allowing your savings to grow.
Tips for growing your emergency savings effectively
Growing your emergency savings effectively is essential for financial stability. There are several practical tips to help you increase your savings over time. One effective method is to automate your savings. By setting up an automatic transfer from your checking account to your savings account each month, you ensure that you’re consistently contributing to your fund without thinking about it.
Set Clear Goals
Setting specific savings goals can motivate you to save more. Determine how much you want to save and by when. Break your larger goal into smaller, more manageable milestones. This process can make saving feel less overwhelming.
Review Monthly Expenses
Take a close look at your monthly spending. Identify areas where you can cut back. For example, consider reducing dining out or canceling subscriptions you don’t use. Redirect these savings into your emergency fund.
- Use budgeting apps to track your expenses.
- Allocate funds explicitly for your savings after reviewing monthly expenses.
- Create a spending plan to stick to your budget.
Another effective strategy is to find ways to boost your income. This could be through freelance work, part-time jobs, or selling items you no longer need. Use any extra income to contribute directly to your emergency savings. Additionally, consider taking advantage of windfalls like tax refunds or bonuses by putting those funds straight into your savings.
Lastly, it’s crucial to keep your savings fund separate from your everyday spending money. By placing your emergency fund in a distinct account, you can reduce the temptation to dip into it for non-emergencies. Look for accounts that offer competitive interest rates, which can help grow your savings even further.
FAQ – Frequently Asked Questions about Emergency Fund Strategies
What is an emergency fund?
An emergency fund is a savings account set aside specifically for unexpected expenses, like medical bills or home repairs.
How much should I save for my emergency fund?
A good rule of thumb is to save three to six months’ worth of living expenses to ensure financial stability.
Where is the best place to keep my emergency fund?
High-yield savings accounts and money market accounts are typically the best places to keep your emergency funds due to their safety and accessibility.
What are effective strategies for growing my emergency savings?
Automate your savings, set clear goals, review your expenses, and consider finding additional income sources to boost your emergency fund.