High-Yield Savings 2026: Discover Banks with 5.15% APY or More
Anúncios
Unlocking Your Wealth: Finding the Best High-Yield Savings Accounts in 2026
In an ever-evolving financial landscape, making your money work harder for you is not just a desire, but a necessity. As we look towards 2026, the hunt for the best High-Yield Savings 2026 accounts offering competitive Annual Percentage Yields (APYs) becomes more crucial than ever. Gone are the days when a paltry 0.01% APY was the norm. Today, savvy savers are seeking out institutions that provide significantly higher returns, ideally 5.15% APY or even more, to truly combat inflation and accelerate their financial growth.
Anúncios
This comprehensive guide is designed to equip you with the knowledge and tools needed to navigate the world of high-yield savings accounts in 2026. We’ll delve into what to look for, which banks are leading the charge, and how to ensure your hard-earned money is not just sitting idle, but actively growing. Whether you’re saving for a down payment, a dream vacation, or simply building an emergency fund, maximizing your interest earnings is a smart financial planning move.
The Resurgence of High-Yield Savings: Why 2026 is Your Year
The economic climate leading into 2026 has created a fertile ground for high-yield savings accounts. Central bank policies, inflation concerns, and increased competition among financial institutions have driven interest rates upwards, making it a prime time for consumers to capitalize on these offerings. Historically, high-yield accounts have been a powerful tool for wealth accumulation, providing a safe and liquid option for your funds while still generating substantial returns. For those focusing on High-Yield Savings 2026, understanding these underlying economic forces is key to appreciating the current opportunities.
Anúncios
But what exactly constitutes a ‘high-yield’ account? While the definition can fluctuate with market conditions, in 2026, we’re specifically targeting accounts that offer 5.15% APY or more. This benchmark isn’t arbitrary; it represents a significant step up from traditional savings accounts and provides a meaningful return that can make a real difference to your financial future. These accounts are typically offered by online-only banks or credit unions, which often have lower overheads than traditional brick-and-mortar institutions, allowing them to pass on those savings to their customers in the form of higher interest rates.
The benefits extend beyond just the higher APY. Many high-yield accounts come with minimal fees, easy online access, and FDIC (or NCUA for credit unions) insurance, ensuring your deposits are protected up to the legal limits. This combination of high returns, low costs, and security makes them an incredibly attractive option for any saver looking to optimize their finances.
Decoding APY: More Than Just a Number
When comparing High-Yield Savings 2026 options, you’ll constantly encounter the term APY, or Annual Percentage Yield. While it might seem straightforward, understanding its nuances is crucial. APY reflects the real rate of return earned on a savings account, taking into account the effect of compounding interest. This means that not only do you earn interest on your initial deposit, but you also earn interest on the interest that has already accumulated. The more frequently interest is compounded (e.g., daily vs. monthly), the higher the effective APY, even if the stated interest rate is the same.
For example, an account advertising a 5.00% interest rate compounded daily will have a slightly higher APY than an account with a 5.00% interest rate compounded monthly. When you’re dealing with substantial savings, these small differences can add up significantly over time. Always look for the APY, not just the interest rate, when comparing accounts to get the true picture of your potential earnings.
Furthermore, be aware that APYs can be variable. This means the bank can change the rate at any time based on market conditions. While banks typically notify customers of changes, it’s wise to keep an eye on your account statements and stay informed about current rates. Some banks might offer promotional APYs for a limited time, so always read the fine print to understand if the high rate is sustainable or temporary.
Key Factors to Consider When Choosing a High-Yield Savings Account
Beyond the attractive 5.15% APY, several other factors should influence your decision when selecting a High-Yield Savings 2026 account. A holistic approach ensures you pick an account that not only offers great returns but also aligns with your financial habits and needs.
Minimum Balance Requirements and Fees
Many high-yield accounts come with specific minimum balance requirements to earn the advertised APY or to avoid monthly maintenance fees. Some accounts might require an initial deposit of a few hundred dollars, while others might ask for several thousands. Ensure you can comfortably meet these requirements to avoid fees that could eat into your interest earnings. Similarly, scrutinize any potential fees – ATM fees, wire transfer fees, or excessive transaction fees – that could diminish the overall value of the account.
FDIC or NCUA Insurance
This is non-negotiable. Always verify that your chosen bank is FDIC-insured (for banks) or NCUA-insured (for credit unions). This insurance protects your deposits up to $250,000 per depositor, per institution, in the event of a bank failure. This provides a critical layer of security, making high-yield savings accounts a safe place for your money, despite their higher returns.
Accessibility and Digital Tools
Since many of the top high-yield accounts are offered by online-only banks, consider the ease of managing your account. Do they offer a user-friendly mobile app? Can you easily transfer funds to and from your external bank accounts? What are their customer service options (phone, chat, email)? Seamless digital access and reliable customer support are vital for a positive banking experience.
Linked Accounts and Transfers
How easy is it to link your high-yield savings account to your primary checking account? Look for banks that offer quick and free electronic transfers (ACH transfers) to ensure you can move your money efficiently when needed. Some banks might have limits on the number of transfers or the amount that can be transferred, so it’s good to be aware of these policies.
Top Contenders for High-Yield Savings in 2026 (5.15% APY or More)
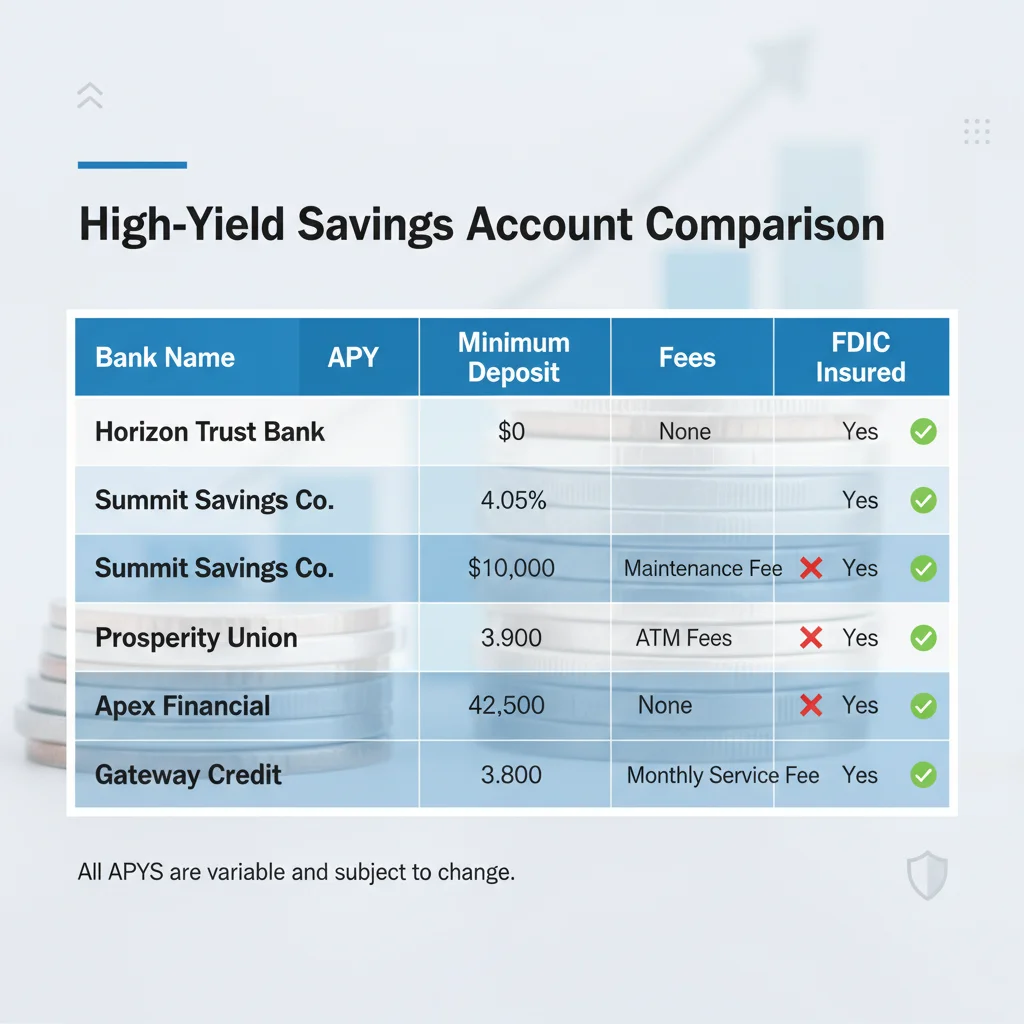
While specific rates and offerings can change, certain types of institutions and emerging players are consistently at the forefront of offering competitive APYs. As we head into 2026, here’s a look at the landscape and what to expect from banks aiming for that 5.15% APY benchmark or higher:
Online-Only Banks
These institutions are typically your best bet for finding the highest APYs. Without the overhead of physical branches, they can pass those savings onto their customers. Look for names like:
- Ally Bank: Consistently a leader in high-yield offerings, known for its user-friendly interface and no monthly maintenance fees. Their APY often hovers at the top of the market.
- Discover Bank: Another strong contender, offering competitive rates, 24/7 customer service, and no monthly fees.
- Synchrony Bank: Often features very attractive APYs, typically with no minimum balance requirements or monthly fees.
- Marcus by Goldman Sachs: Known for its straightforward approach, competitive rates, and excellent customer service.
- Capital One 360 Performance Savings: Offers solid rates with no fees or minimums, integrated well with other Capital One products.
These banks are likely to be among the first to offer 5.15% APY or more as market conditions permit, making them prime targets for your High-Yield Savings 2026 search.
Credit Unions
Often overlooked, credit unions can also offer highly competitive savings rates, sometimes even surpassing traditional banks. They are member-owned, which means their profits are often returned to members in the form of better rates and lower fees. While their online presence might vary, many have robust digital platforms. Always check for NCUA insurance.
Fintech Companies and Neobanks
The rise of financial technology (fintech) companies and neobanks (digital-only banks) continues to disrupt the traditional banking sector. These innovative platforms often leverage technology to offer streamlined services and attractive rates. While some might partner with FDIC-insured banks to hold deposits, it’s crucial to verify their insurance status and regulatory compliance. Examples include Chime, Varo, and other emerging platforms that often offer compelling rates and unique features designed for digital-native users. Keeping an eye on these agile players is essential for anyone seeking the cutting edge of High-Yield Savings 2026.
Maximizing Your Returns: Strategies for High-Yield Savings
Simply opening a High-Yield Savings 2026 account is the first step; optimizing its potential requires a few strategic considerations:
Automate Your Savings
Set up automatic transfers from your checking account to your high-yield savings account on a regular basis (e.g., weekly, bi-weekly, or monthly). This ‘set it and forget it’ approach ensures consistent contributions, leveraging the power of compounding interest over time without you having to actively think about it.
Laddering Your Savings
For larger sums, consider a savings ladder. While typically used for Certificates of Deposit (CDs), a similar principle can be applied to high-yield savings if you anticipate needing portions of your money at different times. This involves segmenting your savings into different accounts or ‘buckets’ within a single account, each earmarked for a specific goal or timeframe. This can help you manage liquidity while still earning high interest on the bulk of your funds.
Stay Informed About Rate Changes
As mentioned, APYs are variable. Make it a habit to periodically check the rates offered by your bank and its competitors. If your bank’s rate drops significantly, don’t hesitate to switch to another institution offering a better APY. The process of transferring funds between online banks has become increasingly seamless.
Understand Withdrawal Limits
High-yield savings accounts, by law, historically had limits on the number of convenient withdrawals or transfers you could make per month (Regulation D). While Regulation D was suspended indefinitely in 2020, banks can still impose their own limits. Be aware of your bank’s specific policies to avoid fees or account closures if you frequently need to access your funds. For funds you need daily access to, a high-yield checking account might be a better fit, though these typically offer lower APYs.
The Future of High-Yield Savings: Beyond 2026
The financial landscape is always in flux, and what holds true for High-Yield Savings 2026 might evolve in subsequent years. However, several trends suggest that competitive interest rates for savings are likely to persist, albeit with fluctuations.
Continued Digitalization
The shift towards digital banking is irreversible. As more consumers embrace online and mobile banking, traditional banks will continue to face pressure from online-only institutions and fintechs, driving innovation and competitive rates. This means more options and potentially higher APYs for savers.
Interest Rate Environment
While central bank policies and inflation are cyclical, the general trend towards a more dynamic interest rate environment means that rates are unlikely to stagnate at historically low levels for extended periods. This offers continued opportunities for high-yield savings accounts to remain attractive.
Personalized Financial Tools
Expect more personalized financial management tools integrated with high-yield savings accounts. AI-powered insights, automated budgeting, and seamless integration with other financial products will likely become standard, further enhancing the value proposition of these accounts.
For individuals, the key will always be vigilance and adaptability. Regularly reviewing your financial products, staying informed about market conditions, and being willing to switch providers are essential habits for maximizing your savings potential, not just in 2026 but for years to come.
Potential Pitfalls and How to Avoid Them
While High-Yield Savings 2026 accounts offer significant advantages, it’s important to be aware of potential downsides and how to mitigate them:
Introductory vs. Standard APY
Some banks might offer an exceptionally high APY as an introductory offer. After a certain period, this rate could revert to a much lower standard rate. Always clarify if the advertised 5.15% APY (or higher) is a permanent or temporary rate. Read the terms and conditions carefully to avoid disappointment.
Hidden Fees
While many high-yield accounts boast no monthly fees, always check for other potential charges. These could include fees for excessive withdrawals, paper statements, foreign transactions, or inactivity. A thorough review of the fee schedule is crucial.
Customer Service Quality
Online banks, while efficient, may not always offer the same level of personalized customer service as a local branch. Before committing, research customer reviews regarding their support channels, response times, and problem-resolution capabilities. Good customer service is invaluable when you encounter issues.
Technology Dependence
If you’re not comfortable with digital banking, an online-only high-yield account might present a learning curve. Ensure you have reliable internet access and are comfortable managing your finances through a website or mobile app. Most online platforms are intuitive, but it’s a factor to consider.
Conclusion: Your Path to Smarter Savings in 2026
The quest for the best High-Yield Savings 2026 accounts offering 5.15% APY or more is a financially rewarding endeavor. By understanding the mechanisms of APY, evaluating key account features, and staying informed about the top contenders, you can make an educated decision that significantly boosts your savings growth.
Remember, the goal is not just to save money, but to grow it intelligently. High-yield savings accounts provide a safe, liquid, and increasingly profitable avenue to achieve your financial objectives. Don’t let your money sit idle in a low-interest account. Take the proactive step to research, compare, and open an account that aligns with your financial aspirations for 2026 and beyond. Your future self will thank you for making your money work as hard as you do.
Start your journey today by exploring the options and taking control of your financial destiny. The opportunity to earn substantial interest on your savings is here, and 2026 is the year to seize it.