Navigating Student Loan Repayment in 2026: A Step-by-Step Guide to New Programs
Anúncios
The landscape of student loan repayment is constantly evolving, and for many borrowers, 2026 will bring significant changes and new opportunities. Whether you’re a recent graduate or have been managing your student debt for years, understanding the latest programs and strategies is crucial for financial success. This comprehensive guide will walk you through everything you need to know about student loan repayment 2026, helping you navigate the complexities and make informed decisions.
Student loan debt remains a substantial burden for millions, and the government, alongside private lenders, frequently adjusts policies to address economic shifts and borrower needs. The year 2026 is poised to be a pivotal year, with several new initiatives and refined existing programs coming into full effect. Our goal is to demystify these changes, providing you with a clear, actionable roadmap to manage your student loans effectively. From understanding the nuances of income-driven repayment plans to exploring refinancing options, we’ve got you covered.
Understanding the Current Student Loan Landscape
Before diving into what 2026 holds, it’s essential to grasp the current state of student loan repayment. For many, the recent pauses and subsequent resumption of payments have been a rollercoaster. Federal student loans, in particular, have seen significant policy adjustments, including interest rate changes, payment pauses, and the introduction of new repayment options. Private student loans, while not subject to federal policies, also require careful consideration due to their different terms and conditions.
Anúncios
The federal student loan system is designed to offer various repayment plans to accommodate different financial situations. These include standard repayment, graduated repayment, extended repayment, and several income-driven repayment (IDR) plans. Each plan has its own eligibility criteria, payment structure, and potential for loan forgiveness. Understanding these basic options is the first step in formulating a robust strategy for student loan repayment 2026.
Key Developments Leading to 2026
- Payment Pause and Resumption: The COVID-19 pandemic led to an unprecedented pause in federal student loan payments and interest accrual. The eventual resumption brought challenges for many borrowers, highlighting the need for stable and predictable repayment options.
- IDR Account Adjustment: A significant one-time adjustment to IDR payment counts has been ongoing, aiming to correct past administrative errors and provide credit towards forgiveness for periods that should have counted. This adjustment could significantly impact borrowers nearing forgiveness in 2026.
- Introduction of the SAVE Plan: The new Saving on a Valuable Education (SAVE) Plan has replaced the REPAYE plan, offering more generous terms, including lower monthly payments for many borrowers and a higher income exemption before payments are required. This plan is a game-changer for student loan repayment 2026.
- Public Service Loan Forgiveness (PSLF) Enhancements: While PSLF has been around for a while, ongoing efforts to streamline the process and expand eligibility have made it a more viable option for public servants.
The SAVE Plan: A Cornerstone of Student Loan Repayment in 2026
The Saving on a Valuable Education (SAVE) Plan is arguably the most impactful development for federal student loan borrowers in recent years, and its full benefits will be increasingly felt in 2026. The SAVE plan offers several advantages over previous income-driven repayment options, making it a critical tool for managing your student debt.
How the SAVE Plan Works
The SAVE Plan calculates your monthly payment based on your income and family size, but with more favorable terms than its predecessors. Here are the key features:
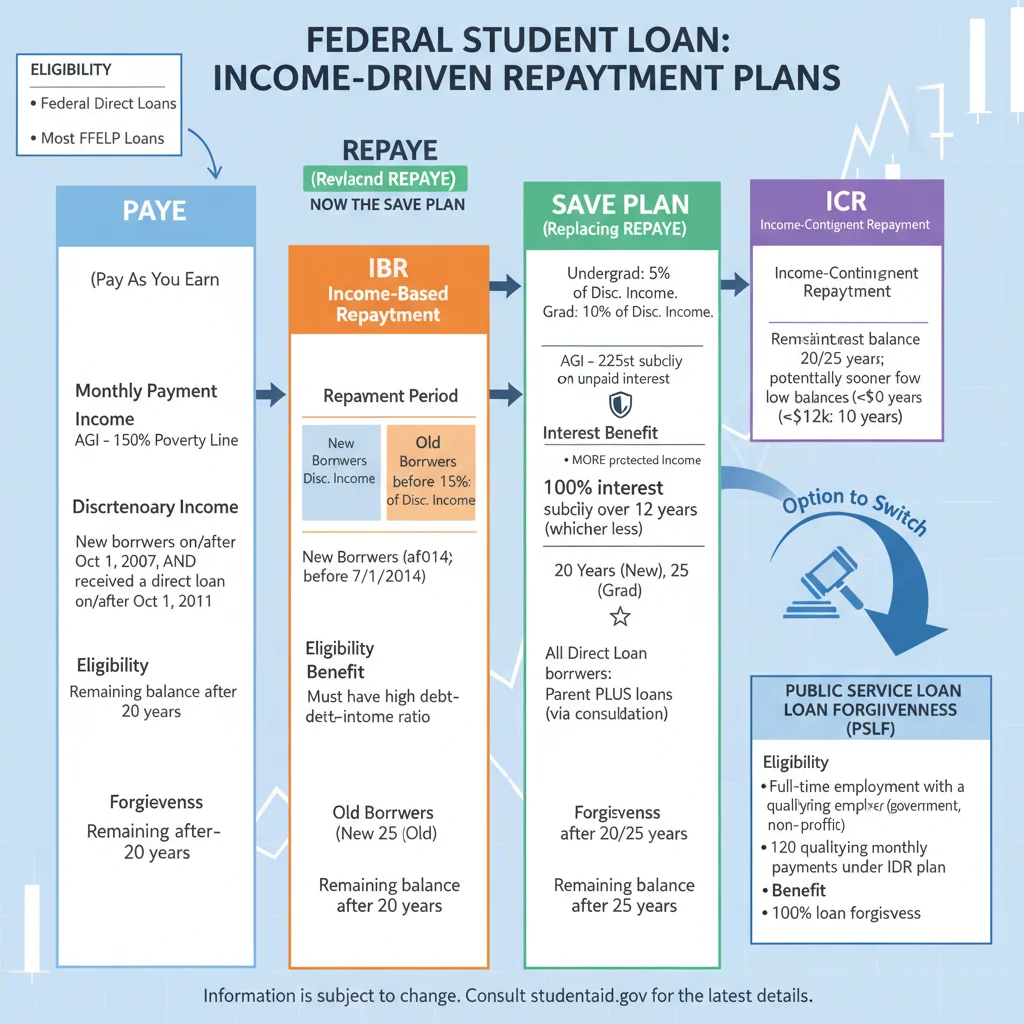
- Higher Income Exemption: The amount of income protected from payment calculations is significantly higher, meaning many low-income borrowers will have a $0 monthly payment. Specifically, the SAVE Plan protects 225% of the federal poverty line, up from 150% under REPAYE.
- No Accumulation of Unpaid Interest: This is a major benefit. If your calculated monthly payment doesn’t cover the interest that accrues, the government will cover the remaining interest. This prevents your loan balance from growing, even if you’re making low or $0 payments. This feature is crucial for long-term financial health and makes the SAVE Plan highly attractive for student loan repayment 2026.
- Lower Payments for Undergraduate Loans: For undergraduate loans, monthly payments are capped at 5% of your discretionary income, down from 10% under REPAYE. This change is fully implemented by July 2024, impacting borrowers significantly in 2026.
- Shorter Path to Forgiveness for Smaller Balances: Borrowers with original loan balances of $12,000 or less can receive forgiveness after as little as 10 years of payments, with an additional year added for every $1,000 borrowed above that amount. The maximum repayment period for forgiveness is 20 years for undergraduate loans and 25 years for graduate loans.
Enrolling in the SAVE Plan can significantly reduce your financial burden and provide a clearer path to loan forgiveness. It’s especially beneficial for borrowers with lower incomes relative to their loan balances. If you’re struggling with high monthly payments, the SAVE Plan should be your first consideration for student loan repayment 2026.
Other Income-Driven Repayment (IDR) Plans in 2026
While the SAVE Plan is a standout, other IDR plans will still be available for federal student loan borrowers in 2026. It’s important to understand these options as well, as one might be a better fit for your specific circumstances.
Pay As You Earn (PAYE)
The PAYE plan generally caps payments at 10% of your discretionary income, but never more than what you would pay under the Standard Repayment Plan. Loan forgiveness occurs after 20 years of qualifying payments. Eligibility for PAYE is generally restricted to newer borrowers (those who took out their first federal loan on or after October 1, 2007, and received a disbursement of a direct loan on or after October 1, 2011).
Income-Based Repayment (IBR)
IBR caps payments at 10% or 15% of your discretionary income, depending on when you took out your loans. Forgiveness is granted after 20 or 25 years of qualifying payments. IBR is generally available to a broader range of borrowers than PAYE.
Income-Contingent Repayment (ICR)
ICR is the oldest IDR plan and calculates payments as the lesser of 20% of your discretionary income or what you would pay on a fixed 12-year repayment plan, adjusted by income. Forgiveness occurs after 25 years. ICR is the only IDR plan available for Parent PLUS loans (after consolidation into a Direct Consolidation Loan).
Choosing the right IDR plan is critical for effective student loan repayment 2026. It’s recommended to use the Federal Student Aid Loan Simulator tool to compare payments across different plans based on your specific financial situation. Remember that your choice of plan can significantly impact your monthly payments, the total amount you pay over time, and your eligibility for loan forgiveness.
Public Service Loan Forgiveness (PSLF) in 2026
For individuals working in eligible public service jobs, the Public Service Loan Forgiveness (PSLF) program offers a powerful path to debt relief. PSLF forgives the remaining balance on Direct Loans after you’ve made 120 qualifying monthly payments while working full-time for a qualifying employer. With ongoing improvements to the program, PSLF will continue to be a vital option for student loan repayment 2026.
Key Aspects of PSLF
- Qualifying Employment: This includes government organizations (federal, state, local, or tribal), not-for-profit organizations that are tax-exempt under Section 501(c)(3) of the Internal Revenue Code, and some other non-profit organizations that provide specific public services.
- Qualifying Loans: Only Direct Loans are eligible for PSLF. If you have FFEL Program loans or Perkins Loans, you’ll need to consolidate them into a Direct Consolidation Loan to become eligible.
- Qualifying Payments: Payments must be made under a qualifying repayment plan (typically an IDR plan), for the full amount due, and within 15 days of the due date.
- Employment Certification: Regularly certifying your employment is crucial to track your progress towards the 120 payments. This helps identify and correct any issues early.
The Department of Education has made efforts to simplify the PSLF process and address past issues that prevented eligible borrowers from receiving forgiveness. These improvements mean that more borrowers may find success with PSLF in 2026. If you’re in public service, make sure you understand the updated requirements and regularly verify your eligibility and payment counts.
Refinancing and Consolidation for Student Loan Repayment in 2026
Beyond federal programs, two other significant strategies for managing student loans are refinancing and consolidation. While often confused, they serve different purposes and have distinct implications for your student loan repayment 2026 strategy.
Student Loan Consolidation (Federal)
Federal student loan consolidation allows you to combine multiple federal student loans into a single Direct Consolidation Loan. This results in one monthly payment and often a new, weighted average interest rate. The primary benefits of federal consolidation include:
- Simpler Payments: One bill, one due date.
- Access to IDR Plans: Some older federal loans (like FFEL or Perkins) become eligible for certain IDR plans and PSLF only after consolidation into a Direct Loan.
- Potentially Lower Monthly Payments: By extending the repayment term, though this may increase the total interest paid over the life of the loan.
A key consideration for student loan repayment 2026 is that consolidating federal loans can sometimes reset your payment count for IDR or PSLF forgiveness, though recent adjustments aim to mitigate this for some borrowers. Always check the specific rules before consolidating.
Student Loan Refinancing (Private)
Refinancing involves taking out a new loan, typically from a private lender, to pay off one or more existing student loans (federal or private). The goal is usually to secure a lower interest rate, a different loan term, or both. Benefits include:
- Lower Interest Rate: If you have excellent credit, you might qualify for a lower interest rate, saving you money over the life of the loan.
- Reduced Monthly Payments: By extending the loan term, or a lower interest rate.
- Simplified Payments: Similar to consolidation, you’ll have one payment to a single lender.
However, refinancing federal loans into a private loan means losing federal benefits such as access to IDR plans, loan forgiveness programs (like PSLF or IDR forgiveness), and deferment/forbearance options. This is a significant trade-off that requires careful consideration for your student loan repayment 2026 plan.
Strategies for Effective Student Loan Repayment in 2026
With a clearer understanding of the programs available, let’s explore actionable strategies to optimize your student loan repayment in 2026.
1. Assess Your Financial Situation Annually
Your income, family size, and financial goals can change. It’s crucial to reassess your student loan strategy annually, especially if you’re on an IDR plan, as these plans require annual recertification of income and family size. Failing to recertify can lead to higher payments or capitalization of interest.
2. Understand Your Loan Types
Differentiate between federal and private loans. Federal loans offer protections and programs that private loans do not. Knowing what you have is the first step to choosing the right repayment strategy for student loan repayment 2026.
3. Maximize Federal Benefits First
Before considering private refinancing, explore all federal options. The SAVE Plan, other IDR plans, and PSLF offer protections and potential forgiveness that private loans cannot replicate. These benefits are invaluable, especially if your income is unstable or you anticipate working in public service.
4. Consider Aggressive Repayment if Possible
If your financial situation allows, making extra payments or choosing a shorter repayment term can save you a significant amount in interest over the life of your loan. Even small extra payments can make a difference. This strategy is particularly effective for borrowers with higher interest rates or those who want to be debt-free sooner.
5. Build an Emergency Fund
Having an emergency fund (3-6 months of living expenses) is crucial. It provides a safety net if you face unexpected financial hardship, preventing you from missing student loan payments and incurring fees or damaging your credit.
6. Explore Employer Assistance Programs
Some employers offer student loan repayment assistance as a benefit. Check with your HR department to see if your company provides any such programs. This can be a fantastic, often overlooked, resource for student loan repayment 2026.
7. Be Wary of Scams
Unfortunately, student loan scams are prevalent. Be skeptical of companies promising immediate loan forgiveness or requiring upfront fees for services you can get for free from your loan servicer or the Federal Student Aid website. Always go directly to official sources for information and assistance.
Preparing for 2026: A Checklist
To ensure you’re fully prepared for student loan repayment 2026, follow this checklist:
- Review Your Loan Details: Log into your loan servicer’s website and the Federal Student Aid website (studentaid.gov) to confirm your loan types, balances, and interest rates.
- Update Contact Information: Ensure your loan servicers and the Department of Education have your current address, phone number, and email.
- Research Repayment Options: Use the Federal Student Aid Loan Simulator to compare different repayment plans, especially the SAVE Plan, and see which one best fits your financial situation.
- Consider Consolidating (if applicable): If you have older federal loans (FFEL, Perkins), consider consolidating them into a Direct Loan to gain access to more federal benefits like the SAVE Plan and PSLF.
- Certify Employment for PSLF: If you’re pursuing PSLF, ensure your employment is certified regularly.
- Recertify IDR Plans: If you’re on an IDR plan, remember to recertify your income and family size annually to keep your payments accurate and avoid interest capitalization.
- Create a Budget: Develop a realistic budget that includes your student loan payments. This will help you stay on track and identify areas where you can save or make extra payments.
- Set Up Auto-Pay: Many servicers offer a small interest rate reduction (typically 0.25%) for setting up automatic payments. This also helps ensure you never miss a payment.
- Stay Informed: Keep an eye on official announcements from the Department of Education and your loan servicer regarding any new policies or changes.
The Future of Student Loan Repayment Beyond 2026
While this guide focuses on student loan repayment 2026, it’s important to remember that the student loan landscape is dynamic. Policy discussions around broader student loan forgiveness, further enhancements to IDR plans, and potential changes to federal aid programs are ongoing. Staying informed through reputable sources will be key to adapting your strategy as new developments emerge.
The goal of many of these changes is to create a more equitable and manageable system for borrowers. The SAVE Plan, in particular, represents a significant step towards this goal, offering unprecedented protections against runaway interest and providing clearer paths to forgiveness. As you plan for 2026 and beyond, leverage these programs to your advantage.
Conclusion
Navigating student loan repayment can feel overwhelming, but with the right information and a proactive approach, you can manage your debt effectively. The year 2026 presents both challenges and opportunities, particularly with the full implementation and widespread understanding of the SAVE Plan and ongoing improvements to other federal programs.
By understanding your loan types, exploring federal repayment options like the SAVE Plan, considering consolidation or refinancing strategically, and adopting sound financial habits, you can take control of your student debt. Don’t hesitate to reach out to your loan servicer or consult with a reputable financial advisor if you need personalized guidance. Your journey through student loan repayment 2026 can be one of financial empowerment and progress.