Student Loan Forgiveness 2026: Eligibility, Deadlines, and Updates for Borrowers
Anúncios
Student Loan Forgiveness 2026: What Borrowers Need to Know About Updated Eligibility and Application Deadlines
Student loan debt continues to be a significant financial burden for millions of Americans. As we look towards 2026, understanding the evolving landscape of student loan forgiveness 2026 programs is crucial for borrowers seeking relief. The federal government, along with various state and private initiatives, constantly updates its policies, making it challenging to keep track of what’s available, who qualifies, and how to apply. This comprehensive guide aims to demystify these programs, providing you with the most current information on eligibility, application deadlines, and crucial updates that could impact your financial future.
Anúncios
The past few years have seen unprecedented changes in student loan policies, from payment pauses to significant overhauls of existing forgiveness programs. Navigating these changes requires diligence and an understanding of the specific requirements for each program. Whether you’re a recent graduate, a long-term borrower, or someone considering higher education, being informed about student loan forgiveness 2026 options is your first step towards potential debt reduction.
The Current Landscape of Student Loan Forgiveness Programs
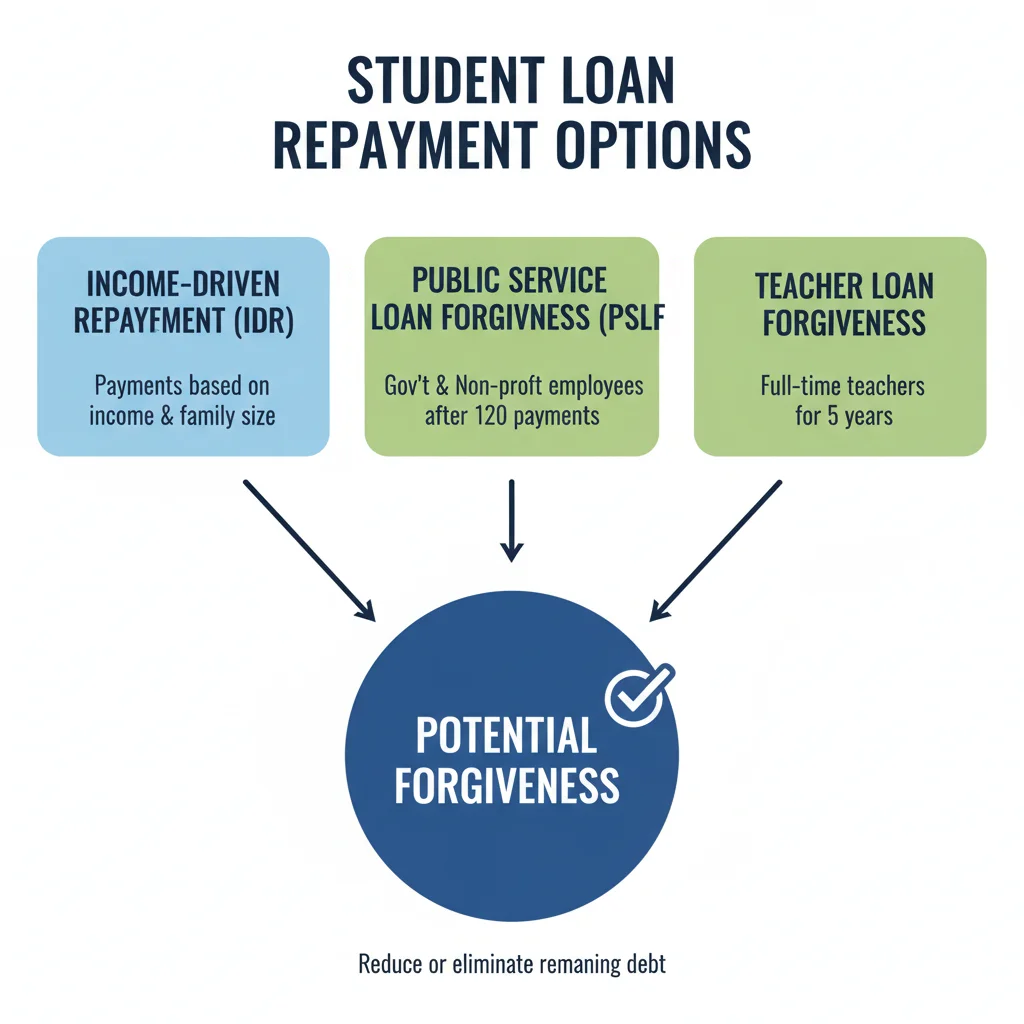
Before diving into the specifics of student loan forgiveness 2026, it’s important to grasp the foundational programs that are likely to continue, albeit with potential modifications. The primary federal programs offering forgiveness include Income-Driven Repayment (IDR) plans, Public Service Loan Forgiveness (PSLF), and various targeted forgiveness programs for specific professions.
Anúncios
Income-Driven Repayment (IDR) Plans
IDR plans are designed to make student loan payments more manageable by capping them at a percentage of your discretionary income. After a certain number of years (20 or 25, depending on the plan and whether you have graduate school loans), any remaining balance is forgiven. The most recent significant development in IDR is the Saving on a Valuable Education (SAVE) Plan, which replaced the REPAYE Plan. The SAVE Plan offers more generous terms, including lower monthly payments for many borrowers and an interest subsidy that prevents your balance from growing due to unpaid interest.
For student loan forgiveness 2026, it’s anticipated that the SAVE Plan will be a cornerstone for many borrowers seeking relief. Key features of the SAVE Plan include:
- Lower Payments: Payments are calculated based on a smaller percentage of discretionary income compared to older IDR plans.
- Interest Subsidy: If your monthly payment doesn’t cover the accrued interest, the government covers the remaining interest, preventing your loan balance from increasing.
- Shorter Forgiveness Timelines: Some borrowers with original principal balances of $12,000 or less could see forgiveness after as little as 10 years of payments.
Understanding how your loan type and income interact with the SAVE Plan is critical. Borrowers should regularly check their eligibility and payment calculations through the Federal Student Aid (FSA) website to ensure they are on the most beneficial plan.
Public Service Loan Forgiveness (PSLF)
PSLF offers forgiveness for the remaining balance on Direct Loans after 120 qualifying monthly payments (10 years) while working full-time for a qualifying employer. This program is specifically designed for individuals working in government (federal, state, local, or tribal) or for certain non-profit organizations. The PSLF program has undergone significant reforms in recent years, including the Limited PSLF Waiver and the IDR Account Adjustment, which have made it easier for many borrowers to qualify for forgiveness by counting previously ineligible payments.
As we approach student loan forgiveness 2026, it’s expected that the streamlined processes and expanded eligibility criteria introduced by these waivers will continue to benefit new applicants. However, borrowers must ensure they:
- Are employed by a qualifying employer.
- Have Direct Loans (or consolidate other federal loans into Direct Loans).
- Are on an income-driven repayment plan.
- Submit an Employment Certification Form (ECF) annually or whenever they change employers.
The PSLF Help Tool on the FSA website is an invaluable resource for tracking progress and ensuring compliance with program requirements. Keep a close eye on any further legislative changes that might affect PSLF in the coming years.
Targeted Forgiveness Programs and 2026 Outlook
Beyond IDR and PSLF, several other programs offer targeted student loan forgiveness 2026 for individuals in specific professions or circumstances. These often have stricter eligibility requirements and may be less widely applicable but can offer substantial relief for those who qualify.
Teacher Loan Forgiveness (TLF)
TLF is available to teachers who work for five consecutive complete academic years in a low-income school or educational service agency. Depending on the subject taught, eligible teachers can receive up to $17,500 in forgiveness for Direct Subsidized and Unsubsidized Loans and Federal Stafford Loans. While not as comprehensive as PSLF, TLF can be a quicker path to relief for qualifying educators.
Perkins Loan Cancellation
Federal Perkins Loans, though no longer issued, still exist for many borrowers. These loans have their own cancellation provisions based on employment in certain public service jobs, such as teaching, nursing, law enforcement, or military service. The percentage of the loan that can be canceled increases over time, potentially reaching 100%.
Total and Permanent Disability (TPD) Discharge
Borrowers who are totally and permanently disabled may be eligible for a TPD discharge, which forgives all federal student loans. Eligibility can be established through documentation from the Department of Veterans Affairs (VA), the Social Security Administration (SSA), or a physician. This program is ongoing and will continue to be a vital option for eligible borrowers in 2026.
Borrower Defense to Repayment
This program offers forgiveness to borrowers whose schools engaged in misconduct, such as misleading students about job prospects or program quality. While the process for borrower defense claims has seen significant changes and backlogs, it remains an important avenue for relief for those defrauded by their institutions. Expect continued efforts to streamline this process into 2026.
Closed School Discharge
If your school closed while you were enrolled or shortly after you withdrew, you might be eligible for a closed school discharge, which cancels 100% of your federal student loans. This is another critical protection for borrowers that will remain in effect.
Eligibility Criteria for Student Loan Forgiveness 2026: What’s New?
The most pressing question for many borrowers is: "Am I eligible for student loan forgiveness 2026?" While the core requirements for programs like PSLF and IDR are expected to remain consistent, there may be subtle but impactful adjustments. It’s crucial to stay updated on these nuances.
Consolidation Requirements
For many federal loan forgiveness programs, particularly PSLF and some IDR benefits, having Direct Loans is a prerequisite. If you have older federal loans (e.g., FFEL Program loans, Perkins Loans), you may need to consolidate them into a Direct Consolidation Loan to become eligible. The IDR Account Adjustment has provided a temporary window for borrowers with older, non-Direct federal loans to consolidate and receive credit for past payments that would not have previously counted towards forgiveness under IDR or PSLF. While the adjustment has a specific end date, the principle of consolidation for eligibility will likely remain relevant for student loan forgiveness 2026.
Income and Family Size
For IDR plans like SAVE, your income and family size are primary determinants of your monthly payment and, by extension, the amount of interest subsidized and the eventual forgiven balance. Changes in your financial situation—such as a decrease in income or an increase in family size—can significantly impact your eligibility and benefits. Borrowers are generally required to recertify their income and family size annually. Failing to do so can lead to higher payments or even removal from the IDR plan, potentially delaying or jeopardizing student loan forgiveness 2026.
Employment Verification for PSLF
For PSLF, consistent and accurate employment verification is paramount. The Department of Education uses the Employment Certification Form (ECF) to confirm your eligibility. Any gaps in employment, changes in employer, or incorrect documentation can affect your progress towards the 120 qualifying payments. The digital PSLF Help Tool has made this process more straightforward, but borrowers must remain diligent in submitting their forms regularly.
Application Deadlines and How to Apply for Student Loan Forgiveness 2026
One of the most critical aspects of securing student loan forgiveness 2026 is understanding and adhering to application deadlines. While some programs, like standard IDR forgiveness, are ongoing, others, particularly those with temporary flexibilities or waivers, have specific end dates.
General Application Process
For most federal student loan forgiveness programs, the application process typically involves:
- Identifying Your Loan Type: Confirm you have federal student loans. Private loans are generally not eligible for federal forgiveness programs.
- Choosing the Right Program: Determine which forgiveness program best suits your circumstances (e.g., PSLF, an IDR plan, Teacher Loan Forgiveness).
- Gathering Documentation: This may include income verification (tax returns, pay stubs), employment verification (W-2s, employer certification forms), and disability documentation.
- Submitting Your Application: Most applications are submitted through the Federal Student Aid (FSA) website or directly to your loan servicer.
- Tracking Your Progress: Keep meticulous records of all submissions and communications. Regularly check your loan servicer’s portal and the FSA website for updates on your application status.
Key Deadlines to Watch for 2026
While a definitive list of all student loan forgiveness 2026 deadlines is impossible to provide years in advance, certain initiatives have established cut-off dates that borrowers should be aware of:
- IDR Account Adjustment: The one-time IDR Account Adjustment, which provides credit for past payments towards IDR and PSLF forgiveness, has a specific deadline. While it has been extended, borrowers with commercially held FFEL loans or Perkins loans need to consolidate into a Direct Loan by a certain date (often late 2023 or early 2024, but check FSA for the latest) to benefit. Missing this deadline could mean losing out on significant payment count adjustments. Ensure you check the official FSA website for the most up-to-date information regarding this crucial adjustment.
- PSLF Waivers: While the Limited PSLF Waiver officially ended, its effects on payment counts are still being processed. Any future temporary waivers or expansions of PSLF would likely come with their own application windows.
- Annual Recertification for IDR Plans: While not a forgiveness deadline, failing to recertify your income and family size for IDR plans annually can lead to your payments reverting to a standard repayment amount, potentially increasing your costs and delaying forgiveness.
It is paramount for borrowers to frequently visit the official Federal Student Aid (FSA) website (studentaid.gov) for the most accurate and current information regarding deadlines and program changes. Government policies are subject to change, and official sources are the most reliable.
Understanding the SAVE Plan and Its Impact on Forgiveness in 2026
The Saving on a Valuable Education (SAVE) Plan is set to be a game-changer for many borrowers seeking student loan forgiveness 2026. As mentioned, it replaces the Revised Pay As You Earn (REPAYE) Plan and offers substantial benefits. Here’s a deeper dive into how it works and what it means for your path to forgiveness:
How Payments Are Calculated
Under the SAVE Plan, your monthly payment is based on your discretionary income, which is the difference between your adjusted gross income (AGI) and 225% of the federal poverty line for your family size. This is a significant improvement over previous IDR plans that used 150% of the poverty line, meaning more of your income is protected, leading to lower monthly payments for many.
- Undergraduate Loans: Payments will be 5% of your discretionary income.
- Graduate Loans: Payments will be 10% of your discretionary income.
- Mixed Loans: A weighted average will be used if you have both undergraduate and graduate loans.
Interest Benefit
Perhaps the most significant feature of the SAVE Plan is its interest subsidy. If your calculated monthly payment is less than the interest that accrues on your loans each month, the government covers the difference. This means your loan balance will not grow due to unpaid interest, even if your payments are $0. This feature directly addresses a major concern for borrowers on IDR plans, where balances often ballooned despite consistent payments, making the prospect of student loan forgiveness 2026 seem out of reach.
Shorter Forgiveness Timelines for Smaller Balances
For borrowers with original principal balances of $12,000 or less, the SAVE Plan offers forgiveness after just 10 years of payments. For every additional $1,000 borrowed above $12,000, an additional year of payments is required, up to a maximum of 20 or 25 years. This accelerated forgiveness timeline is a massive benefit for those with lower loan amounts, providing a much quicker path to debt freedom.
Automatic Enrollment and Recertification
While not fully implemented, there are plans to make IDR enrollment and annual recertification more automatic by allowing the Department of Education to access tax information directly. This would significantly reduce the administrative burden on borrowers and decrease the likelihood of missing deadlines, which could impact student loan forgiveness 2026 prospects.
Potential Future Changes and What to Expect Beyond 2026
The landscape of student loan forgiveness is dynamic, influenced by legislative actions, economic conditions, and administrative priorities. While we focus on student loan forgiveness 2026, it’s prudent to consider potential future changes.
Legislative Action
Future administrations or Congress could introduce new legislation to expand, modify, or even curtail existing forgiveness programs. Large-scale universal forgiveness, while a topic of discussion, would require significant legislative action. Borrowers should remain engaged with news from federal policymakers and advocacy groups.
Economic Factors
Economic downturns or periods of high unemployment can sometimes prompt temporary relief measures, such as payment pauses or expanded eligibility for certain programs. While not predictable, these factors can influence the availability and terms of future forgiveness initiatives.
Administrative Priorities
The Department of Education continuously reviews and refines its policies. This could lead to further streamlining of application processes, additional account adjustments, or new guidance on existing programs. For example, the ongoing efforts to address "forbearance steering" and ensure accurate payment counts for IDR and PSLF demonstrate a commitment to improving program integrity and borrower outcomes. These administrative efforts will continue to shape student loan forgiveness 2026 and beyond.
Navigating Your Student Loan Journey: Best Practices for Borrowers
Regardless of the specific programs available in student loan forgiveness 2026, several best practices can help you manage your loans and maximize your chances of obtaining relief:
- Know Your Loans: Understand whether you have federal or private loans, the type of federal loans (Direct, FFEL, Perkins), your interest rates, and your current repayment plan. This information is critical for determining eligibility for various programs.
- Stay Informed: Regularly check the official Federal Student Aid (FSA) website (studentaid.gov) and reliable financial news sources for updates on student loan policies, program changes, and deadlines.
- Keep Records: Maintain meticulous records of all loan documents, correspondence with your loan servicer, payment histories, and application submissions. This can be invaluable if discrepancies arise.
- Contact Your Servicer: If you have questions or are struggling to make payments, contact your loan servicer immediately. They can help you explore repayment options, including IDR plans, deferment, or forbearance.
- Utilize the FSA Website: The FSA website is a treasure trove of information, tools, and resources. Use the Loan Simulator to explore repayment options, the PSLF Help Tool to track your eligibility, and your dashboard to view your loan details.
- Beware of Scams: Be wary of companies promising "guaranteed" or "immediate" forgiveness for a fee. Most federal programs do not require payment to apply, and you can typically apply for free through the FSA website or your loan servicer.
The Importance of Proactive Planning for 2026 and Beyond
The journey to student loan forgiveness is rarely passive. It requires proactive engagement, continuous monitoring, and a willingness to adapt to policy changes. For those aiming for student loan forgiveness 2026, the time to act is now. Review your current loan status, understand your eligibility for existing programs, and be prepared to take advantage of any new opportunities that arise.
For instance, if you believe you qualify for PSLF, ensure your employment is certified and you are on an eligible repayment plan. If an IDR plan like SAVE seems beneficial, apply or switch to it as soon as possible to start accumulating qualifying payments. The sooner you align your actions with the requirements of a forgiveness program, the sooner you can achieve relief.
Moreover, consider the broader implications of your financial decisions. While forgiveness is a powerful tool, it’s part of a larger financial strategy. Budgeting, saving, and making informed choices about future education or career paths can complement your efforts to reduce student debt. The goal is not just to get rid of debt but to build a stable and prosperous financial future.
Conclusion
The prospect of student loan forgiveness 2026 offers hope for millions of borrowers burdened by educational debt. While the landscape is complex and subject to change, federal programs like Income-Driven Repayment (IDR) plans (especially the SAVE Plan) and Public Service Loan Forgiveness (PSLF) provide established pathways to relief. Targeted programs for specific professions and circumstances also offer significant opportunities.
Key to navigating this environment is staying informed, proactively managing your loans, and diligently adhering to application requirements and deadlines. Utilize official resources like the Federal Student Aid website, maintain thorough records, and be wary of scams. By understanding the updated eligibility criteria and application processes, borrowers can position themselves to take full advantage of the opportunities for student loan forgiveness 2026 and work towards a future free from student debt.
Remember, your financial well-being is a journey, and understanding these programs is a critical step. Don’t hesitate to seek guidance from trusted financial advisors or your loan servicer if you need personalized assistance. The path to forgiveness may require patience and persistence, but the potential rewards are well worth the effort.