2026 Social Security Benefits: What the 3.2% COLA Increase Means for Your Monthly Payments
For millions of Americans relying on Social Security, understanding the annual Cost-of-Living Adjustment (COLA) is paramount. As we look ahead to 2026, the projected Social Security COLA 2026 increase of 3.2% is set to bring significant changes to monthly benefit payments. This adjustment, designed to help beneficiaries keep pace with inflation, will impact a vast array of individuals, from retirees and survivors to those receiving disability benefits. Navigating these changes requires a clear understanding of how COLA is calculated, its historical context, and its implications for your personal finances. This comprehensive guide will delve into every facet of the 2026 COLA, ensuring you are well-informed and prepared for the year ahead.
Anúncios
Understanding the Cost-of-Living Adjustment (COLA)
The Cost-of-Living Adjustment, or COLA, is a critical component of the Social Security system. Its primary purpose is to ensure that the purchasing power of Social Security benefits is not eroded by inflation. Without COLA, the fixed income received by beneficiaries would gradually lose value over time, making it increasingly difficult to afford essential goods and services. The Social Security Administration (SSA) implements COLA annually, with the adjustment typically announced in October of the preceding year and taking effect in January.
How COLA is Calculated
The calculation of COLA is tied directly to the Consumer Price Index for Urban Wage Earners and Clerical Workers (CPI-W). Specifically, the SSA compares the average CPI-W for the third quarter (July, August, and September) of the current year with the average for the third quarter of the most recent year in which a COLA was payable. The percentage increase between these two periods determines the COLA. If there is no increase, or if the index shows a decrease, then no COLA is applied for that year. This methodology ensures that the adjustment reflects real-world changes in the cost of living experienced by a significant portion of the population.
For the Social Security COLA 2026, the 3.2% figure is a projection based on current economic forecasts and inflationary trends. While projections can shift, they provide a strong indication of what beneficiaries can expect. This 3.2% increase, if finalized, would translate directly into higher monthly payments for all eligible Social Security beneficiaries, offering a much-needed boost in a continuously evolving economic landscape.
Anúncios
The Projected 3.2% COLA Increase for 2026
The anticipation of a 3.2% COLA increase for 2026 is a significant development for current and future Social Security recipients. This percentage, while not as high as some of the larger adjustments seen in recent years, still represents a substantial boost designed to help beneficiaries maintain their financial stability amidst ongoing inflation.
Impact on Monthly Payments
A 3.2% increase means that for every $1,000 in monthly Social Security benefits, beneficiaries would see an additional $32. While this might seem modest on its own, it adds up over the year and can make a considerable difference, especially for those with lower fixed incomes. For example, if the average monthly Social Security benefit for retired workers is projected to be around $1,900 in late 2025, a 3.2% COLA would add approximately $60.80 to that payment, bringing it to roughly $1,960.80 per month. These additional funds can help cover rising costs of groceries, utilities, transportation, and other essential expenses.
It’s important to remember that the actual dollar increase will vary for each individual based on their specific benefit amount. Higher earners who receive maximum Social Security benefits will see a larger dollar increase, while those with lower benefits will experience a smaller, but equally important, boost.
Historical Context of COLA Increases
To fully appreciate the Social Security COLA 2026, it’s helpful to look at it within a historical context. COLA adjustments have fluctuated significantly over the decades, reflecting varying economic conditions. In recent years, we’ve seen some notable increases, such as the 5.9% for 2022 and the 8.7% for 2023, driven by exceptionally high inflation. The 3.2% for 2026, while lower than these peaks, is still a healthy increase compared to periods of low inflation where COLA was minimal or even zero.
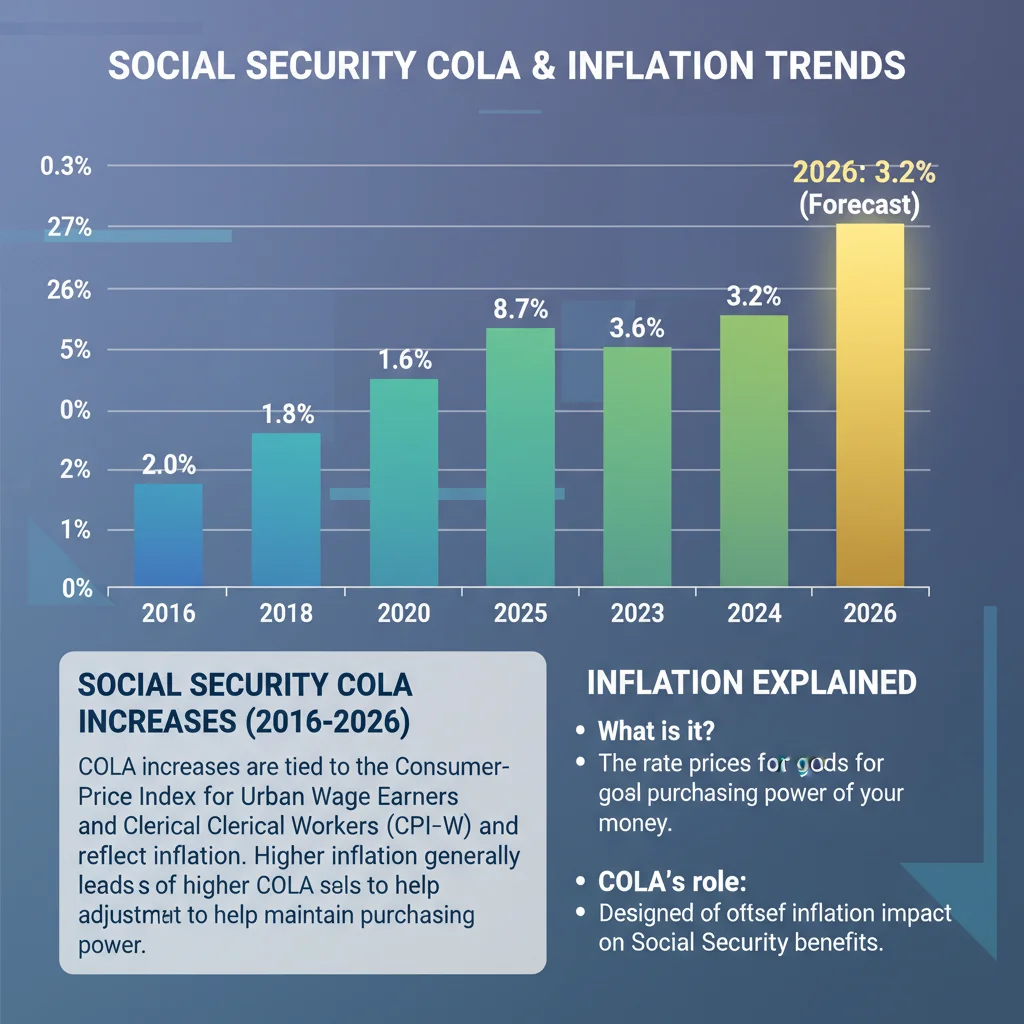
Understanding these historical trends helps beneficiaries anticipate future adjustments and plan accordingly. The consistent application of COLA, even in years of lower inflation, underscores the SSA’s commitment to protecting the financial well-being of its recipients.
Who Benefits from the 2026 COLA?
The Social Security COLA 2026 increase is not limited to just one group of beneficiaries; it extends its reach across various categories of individuals who rely on Social Security payments. This broad impact ensures that the adjustment provides widespread relief and support.
Retirees
The largest group to benefit from the COLA are retirees. Millions of retired workers who have contributed to the Social Security system throughout their working lives will see their monthly checks increase. This is crucial for maintaining their standard of living, especially for those whose Social Security benefits constitute a significant portion of their retirement income. The additional funds can help cover rising healthcare costs, housing, and daily expenses, providing greater financial security in their golden years.
Survivors
Survivor benefits are paid to eligible family members of a deceased worker, including widows, widowers, and dependent children. These benefits are also subject to COLA adjustments. The 2026 increase will help these families cope with the financial challenges that often accompany the loss of a primary wage earner, ensuring that their support payments keep pace with the cost of living.
Individuals with Disabilities
Social Security Disability Insurance (SSDI) beneficiaries will also receive the 3.2% COLA. For individuals living with disabilities, these benefits are often their sole source of income. The increase will provide much-needed relief, allowing them to better manage their living expenses, medical costs, and other disability-related expenditures. Similarly, Supplemental Security Income (SSI) recipients, who are typically low-income individuals who are aged, blind, or disabled, will also see their federal benefit rate adjusted by the same COLA percentage.
In essence, the Social Security COLA 2026 is designed to support all individuals who depend on these vital programs, reinforcing the system’s role as a financial safety net for vulnerable populations.
Potential Impacts Beyond Monthly Payments
While the most direct impact of the Social Security COLA 2026 is on the amount of your monthly benefit payment, the adjustment can have ripple effects across various other aspects of your financial life. Understanding these broader implications is crucial for comprehensive financial planning.
Medicare Premiums
One of the most significant considerations for many Social Security beneficiaries is the interaction between COLA and Medicare Part B premiums. By law, Medicare Part B premiums are often deducted directly from Social Security benefit checks. The ‘hold harmless’ provision typically prevents a beneficiary’s net Social Security payment from decreasing year-over-year due to a Medicare premium increase. However, a higher COLA can sometimes mean that Part B premiums increase more significantly for some beneficiaries, especially those not covered by the hold harmless provision (e.g., new enrollees, those paying income-related monthly adjustment amounts, or those whose premiums are paid by Medicaid).
It’s common for Medicare Part B premiums to be announced around the same time as the COLA, and beneficiaries often find that a portion of their COLA increase is absorbed by higher Medicare costs. Therefore, while your gross Social Security benefit will increase, your net payment might not see the full 3.2% boost.
Taxation of Social Security Benefits
Another important consideration is the potential for increased taxation of Social Security benefits. If your combined income (Adjusted Gross Income + nontaxable interest + half of your Social Security benefits) exceeds certain thresholds, a portion of your Social Security benefits may become taxable. These thresholds are not indexed for inflation, meaning they remain fixed over time. Consequently, a COLA increase, which raises your gross Social Security benefit, could push more beneficiaries above these thresholds, or increase the taxable portion for those already above them.
For individuals filing as single, benefits may be taxable if combined income is between $25,000 and $34,000 (up to 50% taxable) or over $34,000 (up to 85% taxable). For those filing jointly, the thresholds are between $32,000 and $44,000 (up to 50% taxable) or over $44,000 (up to 85% taxable). As the Social Security COLA 2026 increases your income, it’s vital to factor this into your annual tax planning.
Eligibility for Other Assistance Programs
For some beneficiaries, a COLA increase could potentially impact their eligibility for certain low-income assistance programs. Many state and federal programs have income thresholds that determine eligibility for benefits like Medicaid, food stamps, or housing assistance. While designed to help, a higher Social Security payment, even due to COLA, could, in some specific cases, push an individual’s income just above an eligibility limit, potentially reducing or eliminating other vital support. It’s advisable for beneficiaries to review the income limits for any assistance programs they participate in to understand these potential effects.
Planning Your Finances with the 2026 COLA in Mind
Receiving an increase in your Social Security benefits, even a modest one like the projected 3.2% for the Social Security COLA 2026, presents an opportunity to review and adjust your financial plan. Strategic planning can help you maximize the benefit of this increase and ensure your long-term financial security.
Reviewing Your Budget
The first step is to revisit your household budget. Update your income figures to reflect the new, higher Social Security payment. Then, assess your expenses. Have any costs increased significantly? Are there areas where you can optimize spending? The COLA increase can provide a small buffer against rising costs, but a thorough budget review will reveal where those extra dollars can have the most impact.
Consider allocating the additional funds to essential categories first, such as groceries, healthcare co-pays, or utility bills. If you find yourself with a surplus after covering necessities, you can then think about other financial goals.
Addressing Debt
If you have outstanding debts, particularly high-interest credit card debt, using a portion or all of your COLA increase to make extra payments can be a wise strategy. Reducing debt can free up more of your income in the long run and improve your overall financial health. Even small additional payments can significantly shorten the repayment period and reduce the total interest paid.
Building an Emergency Fund
For many retirees, an emergency fund is a critical safety net. Unexpected expenses, such as home repairs or unforeseen medical costs, can quickly derail a carefully planned budget. If you don’t have an emergency fund, or if yours is insufficient, consider directing your Social Security COLA 2026 increase towards building or bolstering this fund. Aim for at least three to six months’ worth of essential living expenses to provide peace of mind.
Saving and Investing
Even in retirement, saving and investing can still play a role. If your basic needs are met and you have a solid emergency fund, consider putting the extra COLA funds into a savings account, a Certificate of Deposit (CD), or other low-risk investment vehicles. While the amounts may be small, they can accumulate over time, providing additional resources for future needs or a legacy for your loved ones. Consult with a financial advisor to determine the best options for your individual circumstances.
Reviewing Your Medicare Coverage
As mentioned, Medicare premiums can impact your net Social Security benefit. Use the COLA announcement as a reminder to review your Medicare coverage during the annual enrollment period. Ensure your current plan still meets your healthcare needs and budget. Sometimes, switching to a different Part D prescription drug plan or a Medicare Advantage plan can lead to significant savings, offsetting potential increases in Part B premiums.
The Future of Social Security and COLA
While the Social Security COLA 2026 provides an immediate benefit, it’s also important to consider the long-term outlook for Social Security and how future adjustments might evolve. The system faces ongoing challenges, primarily related to demographic shifts and funding.
Demographic Challenges
The Social Security system is funded by payroll taxes from current workers, which then pay benefits to current retirees and other beneficiaries. As the baby boomer generation continues to retire and life expectancies increase, the ratio of workers to beneficiaries is declining. This demographic shift puts pressure on the system’s finances, leading to concerns about its long-term solvency.
Projections from the Social Security Trustees indicate that without legislative action, the trust funds may be able to pay only a percentage of scheduled benefits in the coming decades. This doesn’t mean Social Security will disappear, but it does suggest that future generations might receive reduced benefits if no changes are made.
Potential Reforms and Their Impact on COLA
Various proposals for Social Security reform have been debated, including raising the full retirement age, adjusting the payroll tax rate, or changing the COLA calculation method. For instance, some proposals suggest switching to a ‘Chained CPI,’ which typically grows at a slower rate than the CPI-W currently used. If implemented, such a change could result in smaller COLA increases in the future, impacting the purchasing power of benefits over time.
While these are legislative considerations that are subject to political processes, it’s important for beneficiaries and future retirees to stay informed about these discussions. The ongoing dialogue about Social Security’s future underscores the importance of not solely relying on these benefits for retirement and actively engaging in personal financial planning.
Staying Informed
The best way to prepare for future changes is to stay informed. The Social Security Administration (SSA) is the official source for all information regarding benefits and COLA adjustments. Regularly checking their website, reviewing your annual Social Security statement, and consulting with trusted financial advisors can help you navigate the complexities of the system and make informed decisions about your financial future. The Social Security COLA 2026 is a current reality, but understanding the broader context prepares you for what lies ahead.
Conclusion: Maximizing Your 2026 Social Security Benefits
The projected 3.2% Social Security COLA 2026 increase offers a welcome adjustment for millions of beneficiaries. It represents the Social Security Administration’s commitment to helping retirees, survivors, and individuals with disabilities maintain their purchasing power in the face of inflation. While the increase provides a direct boost to monthly payments, its broader implications, particularly concerning Medicare premiums and potential tax impacts, warrant careful consideration.
By actively reviewing your budget, addressing debt, building an emergency fund, and exploring saving opportunities, you can effectively leverage this COLA increase to strengthen your financial position. Furthermore, staying informed about the long-term outlook for Social Security and potential reforms is crucial for comprehensive retirement planning. Embrace this opportunity to refine your financial strategy and ensure a more secure and comfortable future.
Remember, your Social Security benefits are a cornerstone of your financial security. Understanding the nuances of annual adjustments like the Social Security COLA 2026 empowers you to make the most of these vital resources.