Healthcare Reform: Key Changes to Affordable Care Act Impacting Millions Starting January 2026
Anúncios
The landscape of American healthcare is perpetually evolving, and few pieces of legislation have shaped it as profoundly as the Affordable Care Act (ACA). Signed into law in 2010, the ACA has undergone numerous adjustments and faced continuous debate. As we approach January 2026, a new wave of significant changes is poised to take effect, impacting millions of Americans and reshaping the accessibility, affordability, and scope of health insurance coverage. Understanding these upcoming ACA 2026 Changes is not merely a matter of policy interest; it is crucial for individuals, families, and healthcare providers to prepare for what lies ahead.
This comprehensive guide delves into the specifics of these impending reforms, dissecting the key areas where the ACA will see its most notable shifts. From modifications to premium tax credits and cost-sharing reductions to potential expansions in Medicaid and new regulations affecting employer-sponsored plans, we will explore the intricate details that will define healthcare in the coming years. Our aim is to provide clarity amidst complexity, offering actionable insights for those navigating their healthcare options.
Anúncios
Understanding the Genesis of the ACA 2026 Changes
To fully grasp the significance of the ACA 2026 Changes, it’s essential to revisit the foundational principles of the Affordable Care Act. The ACA was designed to expand health insurance coverage, control healthcare costs, and improve the quality of care. It introduced several key provisions, including the individual mandate (later repealed), health insurance marketplaces, subsidies for low- and middle-income individuals, and an expansion of Medicaid eligibility. Over the years, various legislative actions and judicial rulings have refined or challenged these provisions, leading to the current juncture where substantial modifications are on the horizon for 2026.
The impetus for these particular changes stems from a combination of factors: the sunsetting of temporary provisions enacted during the COVID-19 pandemic, ongoing efforts to address perceived shortcomings of the original legislation, and evolving political priorities. For instance, enhanced premium tax credits, which made marketplace plans more affordable for many, were temporarily expanded under the American Rescue Plan Act and subsequently extended. However, their future beyond 2025 has been a subject of intense discussion, leading to the specific adjustments we will see in 2026.
Anúncios
Moreover, the continuous analysis of healthcare utilization patterns, spending trends, and population health outcomes has informed policymakers’ decisions. The goal remains to strike a balance between ensuring broad access to affordable care and maintaining the fiscal sustainability of the healthcare system. The ACA 2026 Changes represent a renewed attempt to achieve this delicate balance, with implications that will ripple across the entire healthcare ecosystem.
Premium Tax Credits and Affordability Subsidies: A Major Overhaul
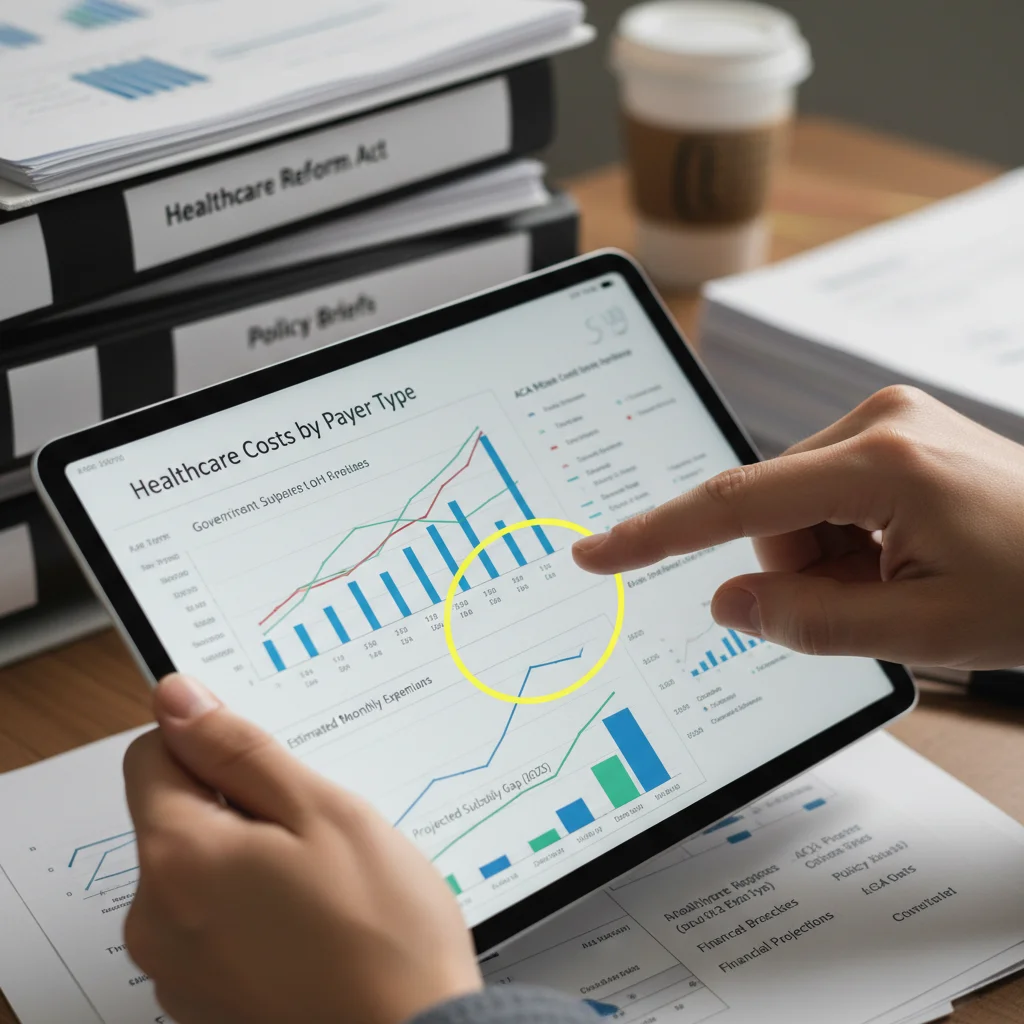
One of the most impactful areas of the ACA 2026 Changes will be the recalibration of premium tax credits (subsidies) and cost-sharing reductions. These financial aids are critical for making health insurance affordable for millions of Americans who purchase plans through the ACA marketplaces. Currently, enhanced subsidies prevent individuals from paying more than 8.5% of their household income for a benchmark silver plan, and they extend eligibility to higher-income individuals who were previously ineligible.
Starting January 2026, several key adjustments are anticipated. The most significant change revolves around the potential expiration or modification of the enhanced subsidies. If these enhancements are allowed to expire without further legislative action, many individuals and families could face substantial increases in their monthly premium costs. This would particularly affect those with incomes above 400% of the federal poverty level (FPL), who currently benefit from subsidies that were previously unavailable to them. Even those below 400% FPL might see their premium contributions rise as the cap on their percentage of income spent on premiums could revert to higher pre-enhancement levels.
Furthermore, the formula used to calculate these subsidies might be revised, potentially altering the benchmark plan against which subsidies are measured or adjusting the income thresholds. Such alterations could subtly but significantly shift who qualifies for how much assistance, leading to a redistribution of financial aid. Understanding these nuances is paramount for anyone currently relying on marketplace subsidies for their health insurance.
The implications extend beyond just premiums. Cost-sharing reductions (CSRs), which lower deductibles, co-payments, and out-of-pocket maximums for eligible individuals, are also intrinsically linked to subsidy eligibility. Changes to the premium tax credit structure could indirectly affect the availability and generosity of CSRs, potentially increasing the financial burden on lower-income enrollees when they access care. Staying informed about these specific adjustments will be crucial for effective financial planning and healthcare decision-making.
Expanding Coverage and Eligibility: Who Benefits and Who Doesn’t?
Beyond subsidies, the ACA 2026 Changes are expected to refine and potentially expand certain aspects of coverage and eligibility, though the precise scope remains subject to ongoing legislative debate. One area of focus is Medicaid expansion. While many states have already expanded Medicaid under the ACA, a handful have not. Efforts to incentivize these remaining states to expand or to create a federal fallback option for their low-income populations could gain traction, potentially extending coverage to hundreds of thousands of uninsured individuals.
Another critical consideration is the ‘family glitch.’ This refers to a loophole where families are often deemed ineligible for marketplace subsidies if an employer offers “affordable” coverage to the employee, even if that coverage is prohibitively expensive for the entire family. While some administrative actions have been taken to address this, more comprehensive legislative solutions might be part of the 2026 reforms, potentially opening up subsidized marketplace plans to many families currently locked out due to this technicality.
The definition of essential health benefits (EHBs) – the 10 categories of services that most health plans must cover – is also an area that could see adjustments. While a complete overhaul is unlikely, there could be clarifications or minor modifications to ensure these benefits align with modern medical practices and public health needs. This could affect everything from mental health and substance use disorder services to maternity care and prescription drug coverage.
However, not all changes might be perceived as beneficial by everyone. Some proposals could introduce stricter eligibility requirements for certain programs or adjust the actuarial value of plans, leading to a different mix of benefits and cost-sharing. It’s imperative for consumers to scrutinize plan offerings carefully after the ACA 2026 Changes take effect to ensure their chosen plan still meets their specific healthcare needs and financial constraints.
Impact on Employer-Sponsored Health Plans and Small Businesses
While much of the ACA’s focus has been on individual marketplaces and Medicaid, the ACA 2026 Changes will also have ripple effects on employer-sponsored health plans, particularly for small businesses. The employer mandate, which requires larger employers to offer affordable health insurance to their full-time employees or pay a penalty, is likely to remain largely intact, but its enforcement and specific thresholds could be reviewed.
For small businesses, the Small Business Health Options Program (SHOP) marketplace and associated tax credits have been underutilized in some areas. Future reforms might aim to streamline these programs, making it easier and more attractive for small employers to offer coverage. This could involve simplified enrollment processes, expanded tax credits for eligible small businesses, or new incentives to encourage participation. The goal would be to reduce the administrative burden and financial strain on small enterprises trying to provide competitive health benefits.
Additionally, the definition of “affordable” coverage for employers might be subject to adjustments. If the threshold for what constitutes an affordable employee contribution changes, it could force some employers to re-evaluate their benefit offerings or face increased penalties. This could lead to a mix of outcomes: some employers might enhance their benefits, while others might struggle to meet the new standards, potentially shifting more employees to the individual marketplace.
The broader economic environment and labor market trends will also interact with these ACA 2026 Changes. As businesses grapple with inflation, labor shortages, and evolving employee expectations, the cost and complexity of providing health insurance remain a significant concern. Policy adjustments that either alleviate or exacerbate these pressures will be closely watched by the business community, underscoring the far-reaching implications of the upcoming reforms.
Preventative Care and Public Health Initiatives
A cornerstone of the original ACA was its emphasis on preventative care, mandating coverage for a wide range of services without cost-sharing. The ACA 2026 Changes are expected to reinforce this commitment, potentially expanding the list of covered preventative services or strengthening guidelines to ensure equitable access. This could include new screenings, vaccinations, or counseling services based on the latest medical evidence and public health recommendations.
Beyond individual preventative services, the reforms might also allocate more resources towards broader public health initiatives. This could involve funding for community health programs, efforts to address social determinants of health (such as housing, food security, and transportation), or enhanced surveillance and response capabilities for infectious diseases. The experience of recent global health crises has underscored the importance of robust public health infrastructure, and the 2026 changes could reflect a renewed investment in these areas.
However, the implementation of these initiatives often faces challenges related to funding, coordination across different levels of government, and public engagement. Effective communication and outreach will be critical to ensure that individuals are aware of and utilize the expanded preventative services and public health resources available to them. The success of these efforts will ultimately depend on a collaborative approach involving federal, state, and local entities, as well as community organizations and healthcare providers.
Prescription Drug Costs and Innovation
The high cost of prescription drugs remains a significant concern for many Americans, and the ACA 2026 Changes are likely to include provisions aimed at addressing this issue. While the ACA itself didn’t directly regulate drug prices comprehensively, subsequent legislation and ongoing policy debates have focused on strategies to lower out-of-pocket costs and promote affordability.
Potential reforms could include measures to increase price transparency, encourage generic and biosimilar competition, or allow Medicare to negotiate drug prices more broadly (which could have spillover effects on commercial plans). There might also be new caps on out-of-pocket prescription drug costs for certain populations, similar to those recently implemented for Medicare beneficiaries. These changes would directly impact individuals with chronic conditions or those requiring expensive specialty medications.
However, efforts to control drug costs must also be balanced against the need to foster pharmaceutical innovation. Policymakers will be navigating the delicate balance between ensuring affordability and maintaining incentives for research and development of new treatments. The specifics of any drug pricing reforms within the ACA 2026 Changes will therefore be a critical area to watch, as they will influence both consumer budgets and the future of medical science.
Navigating the New Healthcare Landscape: What You Need to Do
With the significant ACA 2026 Changes on the horizon, proactive engagement and informed decision-making will be more important than ever. Here’s what individuals, families, and employers should consider:
- Stay Informed: Continuously monitor official government websites (like HealthCare.gov), reputable healthcare news outlets, and policy organizations for the latest updates and clarifications regarding the reforms. The specifics can evolve as legislative processes unfold.
- Re-evaluate Your Coverage: During the open enrollment period for 2026 (typically in late 2025), meticulously review your current health insurance plan. Compare it against new offerings in the marketplace or through your employer. Pay close attention to changes in premiums, deductibles, out-of-pocket maximums, and the scope of covered benefits.
- Understand Subsidy Eligibility: If you currently receive premium tax credits or anticipate needing them, familiarize yourself with the revised income thresholds and calculation methods. Use the official marketplace tools and calculators to estimate your eligibility accurately.
- Consult with Experts: Don’t hesitate to seek advice from qualified insurance brokers, navigators, or healthcare financial advisors. They can provide personalized guidance based on your specific circumstances and help you understand the nuances of the ACA 2026 Changes.
- Employer Considerations: If you are an employer, particularly a small business owner, work closely with your benefits administrator or a professional employer organization (PEO) to understand how the new regulations impact your obligations and options for providing employee health insurance.
- Advocate for Your Needs: Participate in public comment periods, contact your elected officials, and engage with advocacy groups if you have concerns or suggestions regarding the direction of healthcare reform. Your voice can contribute to shaping future policies.
Conclusion: Preparing for a Transformed Healthcare Future
The ACA 2026 Changes represent a pivotal moment in the ongoing evolution of American healthcare. These reforms are not merely bureaucratic adjustments; they are designed to have tangible impacts on the lives of millions, influencing everything from monthly premiums and access to preventative care to the financial stability of healthcare providers. While the precise contours of all changes are still being finalized, the overarching theme is one of adaptation and refinement, driven by a continuous effort to expand coverage, manage costs, and improve health outcomes.
For individuals and families, the coming years will necessitate a proactive approach to understanding their health insurance options. For employers, particularly small businesses, it will require a careful reassessment of benefit strategies. And for the healthcare industry as a whole, it will demand agility and responsiveness to a new regulatory and financial environment.
By staying informed, engaging with available resources, and planning strategically, Americans can navigate the transformed healthcare landscape effectively. The goal of the ACA—to make quality, affordable healthcare a reality for all—remains at the forefront, and the 2026 changes are another step in that complex and continuous journey. The path ahead will undoubtedly have its challenges, but with knowledge and preparation, we can collectively work towards a more resilient and equitable healthcare system for the future.