Inflation Rates Projected to Stabilize at 2.5% by Mid-2026: An In-Depth Analysis
Anúncios
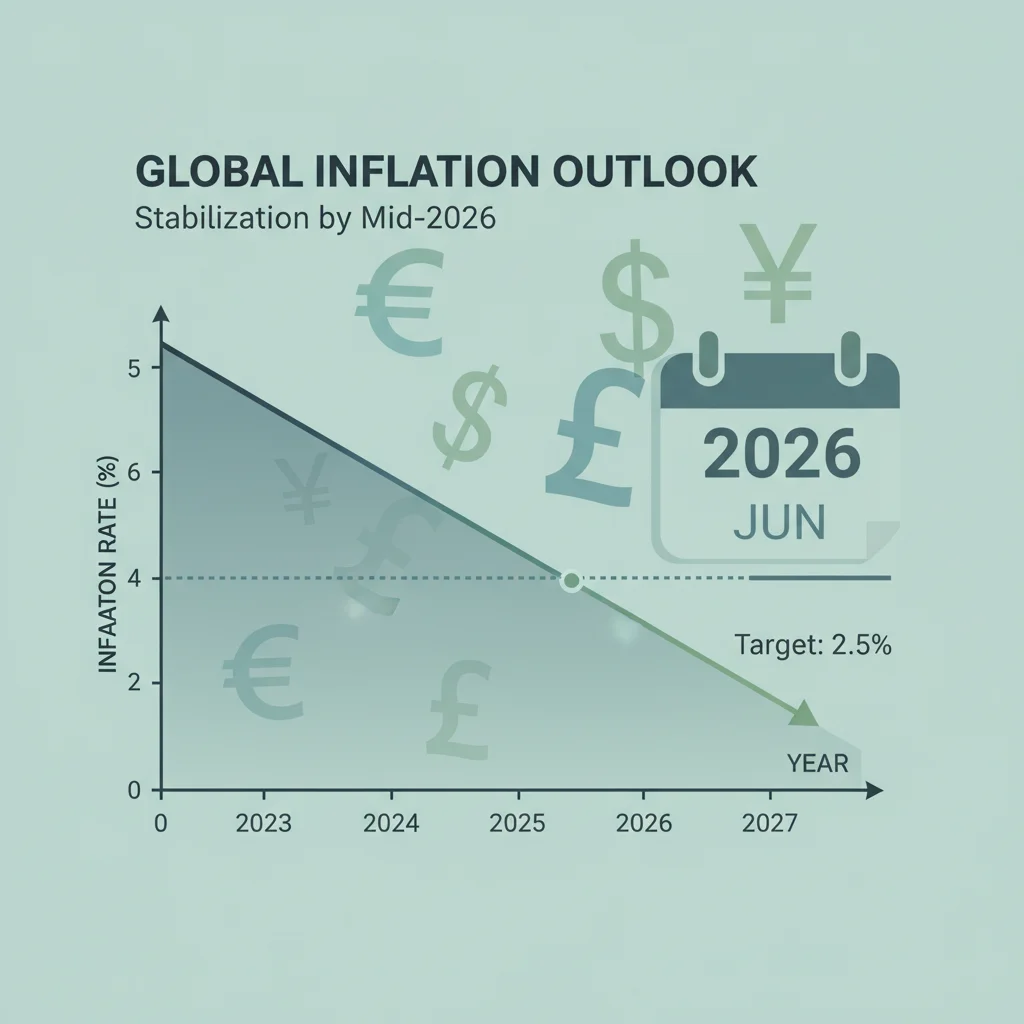
Exclusive Report: Inflation Rates Projected to Stabilize at 2.5% by Mid-2026
The global economy has been on a roller coaster ride over the past few years, with inflation emerging as a dominant concern for policymakers, businesses, and households alike. From supply chain disruptions to geopolitical tensions, numerous factors have contributed to the unprecedented surge in prices. However, a new consensus is emerging among leading economists and financial institutions: a significant moderation is on the horizon. This exclusive report delves into detailed projections suggesting that inflation rates are projected to stabilize at a more manageable 2.5% by mid-2026. This forecast offers a glimmer of hope for a return to economic normalcy and stability.
Anúncios
Understanding the trajectory of inflation is crucial for strategic planning. The journey from peak inflation to a stable 2.5% involves navigating complex economic currents, policy interventions, and evolving market dynamics. This article will explore the underlying factors driving this projection, the potential challenges that could alter this path, and the implications for various sectors of the economy. We will examine the role of central bank policies, global supply chain recovery, energy market trends, and consumer behavior in shaping this optimistic outlook for inflation rate stabilization.
The Current Inflation Landscape: A Retrospective
To appreciate the significance of the projected 2.5% inflation rate stabilization, it’s important to first understand the recent history of inflation. The COVID-19 pandemic triggered an unprecedented economic shock, leading to widespread lockdowns, disruptions in production, and shifts in consumer demand. Governments and central banks responded with massive fiscal and monetary stimulus packages to avert a deeper recession. While these measures provided crucial support, they also injected significant liquidity into the system, laying the groundwork for inflationary pressures.
Anúncios
As economies reopened, a surge in demand met with constrained supply, exacerbated by bottlenecks in global supply chains. Energy prices soared due to geopolitical events and increased demand, further fueling inflationary spirals. Many countries experienced inflation rates not seen in decades, pushing central banks to adopt aggressive monetary tightening policies, including rapid interest rate hikes. These actions, while necessary to combat inflation, also raised concerns about potential economic slowdowns or even recessions. The period from late 2021 through 2023 was characterized by elevated uncertainty and volatility in inflation figures, making the prospect of inflation rate stabilization a highly anticipated development.
Key Drivers Behind the 2.5% Stabilization Projection
Several critical factors are converging to support the forecast of inflation rate stabilization at 2.5% by mid-2026. These drivers are multifaceted, encompassing both policy actions and broader economic trends.
1. Effective Monetary Policy Tightening
Central banks, particularly the U.S. Federal Reserve, the European Central Bank, and the Bank of England, have undertaken significant interest rate hikes to curb inflation. These measures work by increasing the cost of borrowing, thereby reducing demand for goods and services, cooling the economy, and bringing prices down. The lag effect of monetary policy means that the full impact of these rate hikes is still being felt. Economists anticipate that the cumulative effect of these policies will gradually bring inflation back towards target levels. The commitment of central banks to achieving price stability is a cornerstone of this projection for inflation rate stabilization.
2. Normalization of Global Supply Chains
One of the primary drivers of recent inflation was the severe disruption to global supply chains. Lockdowns, labor shortages, and logistical challenges led to higher shipping costs and delays, which were passed on to consumers. Over the past year, many of these bottlenecks have begun to ease. Shipping costs have declined significantly, and production capacity has improved in many sectors. This normalization allows for a more efficient flow of goods, reducing cost pressures and contributing to the overall inflation rate stabilization.
3. Moderation in Energy Prices
Energy prices, particularly for oil and natural gas, have been highly volatile. While geopolitical events can cause sudden spikes, the general trend indicates some moderation. Increased investment in renewable energy sources, diversified energy supplies, and more stable global demand patterns are expected to temper energy price volatility. Lower and more predictable energy costs will have a broad disinflationary effect across various industries, supporting the forecast of inflation rate stabilization.
4. Cooling Labor Markets
Tight labor markets, characterized by low unemployment and strong wage growth, can contribute to inflationary pressures as businesses pass on higher labor costs to consumers. While labor markets remain relatively robust in many advanced economies, there are signs of cooling. Job openings are decreasing, and wage growth, while still elevated, is showing signs of moderating. This rebalancing of labor supply and demand is crucial for achieving sustainable inflation rate stabilization without causing a significant rise in unemployment.
5. Fiscal Consolidation and Reduced Stimulus
Following the massive fiscal stimulus packages implemented during the pandemic, many governments are now embarking on paths of fiscal consolidation. Reduced government spending and a more disciplined approach to public finances can help to rein in aggregate demand, complementing the efforts of central banks. The withdrawal of emergency support measures also reduces the amount of excess liquidity in the economy, further aiding the process of inflation rate stabilization.
Potential Headwinds and Risks to the Projection
While the outlook for inflation rate stabilization at 2.5% is optimistic, it’s important to acknowledge that several risks and headwinds could alter this trajectory. Economic forecasting is inherently uncertain, and unforeseen events can always emerge.
1. Geopolitical Instability
Ongoing geopolitical conflicts and new tensions could disrupt supply chains, impact energy markets, and create uncertainty that spooks investors and consumers. Any significant escalation could reignite inflationary pressures, making the path to inflation rate stabilization more challenging.
2. Persistent Core Inflation
While headline inflation might decline due to easing energy and food prices, core inflation (which excludes these volatile components) could remain sticky. This often reflects underlying demand pressures and services inflation, which can be harder to bring down. If core inflation proves more persistent than anticipated, central banks might need to maintain tighter monetary policies for longer, potentially impacting economic growth.
3. Commodity Price Shocks
Beyond energy, other commodity prices (e.g., metals, agricultural products) could experience unexpected spikes due to weather events, supply disruptions, or increased demand from emerging markets. Such shocks could feed into producer prices and ultimately consumer prices, complicating the journey towards inflation rate stabilization.
4. Policy Errors
Central banks face a delicate balancing act: tightening enough to quell inflation without triggering a severe recession. Over-tightening could lead to an unnecessary economic downturn, while premature easing could allow inflation to re-accelerate. The risk of policy errors, either by central banks or governments, remains a significant factor.
5. Wage-Price Spiral
Although wage growth is showing signs of moderation, a sustained period of high inflation could lead to demands for higher wages across the board, which businesses might then pass on as higher prices. This wage-price spiral could entrench inflation and make the target of inflation rate stabilization at 2.5% more elusive.
Implications of Stabilized Inflation for Businesses and Consumers
The successful inflation rate stabilization at 2.5% would have profound implications across the economy, offering a more predictable environment for planning and investment.
For Consumers:
- Increased Purchasing Power: With inflation under control, the erosion of purchasing power would slow significantly, allowing household incomes to stretch further.
- Greater Financial Certainty: Consumers would face less uncertainty about future price increases, making long-term financial planning (e.g., savings, retirement) more reliable.
- Stable Interest Rates: A stable inflation environment typically leads to more stable and potentially lower interest rates, benefiting borrowers for mortgages, car loans, and other forms of credit.
For Businesses:
- Improved Planning and Investment: Predictable inflation allows businesses to forecast costs and revenues with greater accuracy, encouraging long-term investment and expansion.
- Reduced Cost Pressures: Easing of input costs (raw materials, energy, shipping) would improve profit margins and reduce the need for frequent price adjustments.
- Stable Demand: With consumer purchasing power more secure, businesses can expect more stable demand for their products and services, fostering a healthier economic environment.
- Access to Capital: A stable economic environment with controlled inflation often translates to more favorable lending conditions, making it easier for businesses to access capital for growth.
For Investors:
- Clearer Investment Environment: Reduced inflation uncertainty provides a clearer picture for valuing assets, potentially leading to more rational market behavior.
- Bond Market Stability: Lower and more stable inflation is generally positive for bond markets, as it reduces the risk of inflation eroding the real value of fixed-income returns.
- Sectoral Shifts: As the economy normalizes, investors might shift focus from inflation-hedging assets to growth-oriented sectors, seeking opportunities in a more stable economic landscape.
The Role of International Cooperation
Achieving global inflation rate stabilization is not solely dependent on individual national policies. International cooperation plays a crucial role. Coordinated efforts among central banks and governments can amplify the effectiveness of policy measures. For instance, harmonized monetary policy signals can prevent large capital flows that could destabilize currencies and economies. Furthermore, collaborative initiatives to address global supply chain vulnerabilities, promote energy security, and foster open trade can collectively contribute to a more stable global price environment.
Organizations like the International Monetary Fund (IMF) and the Bank for International Settlements (BIS) continue to monitor global economic conditions and provide platforms for dialogue and coordination among member states. Their analyses and recommendations often highlight the interconnectedness of national economies and the benefits of a collaborative approach to tackling global economic challenges, including inflation.
Looking Beyond 2026: Maintaining Stability
While the projection of inflation rate stabilization at 2.5% by mid-2026 is a significant milestone, the work of maintaining price stability is ongoing. Central banks will need to remain vigilant, adapting their policies to evolving economic data and potential shocks. Governments will also need to pursue prudent fiscal policies that support sustainable growth without reigniting inflationary pressures.
Long-term factors, such as demographic shifts, technological advancements, and climate change, will continue to influence inflation dynamics. For instance, the transition to a greener economy might introduce new cost structures, while automation could exert downward pressure on certain prices. Policymakers will need to consider these structural changes as they aim to keep inflation anchored around target levels in the years beyond 2026.
Conclusion: A Path Towards Predictable Growth
The forecast for inflation rate stabilization at 2.5% by mid-2026 represents a critical turning point for the global economy. After a period of unprecedented price volatility, the convergence of effective monetary policy, normalizing supply chains, moderating energy costs, and cooling labor markets points towards a more predictable and stable economic future. While risks remain, the commitment of policymakers and the inherent resilience of economic systems provide a strong foundation for this optimistic outlook.
This stabilization would usher in an era of greater certainty for consumers, allowing their purchasing power to regain ground, and for businesses, enabling more confident investment and expansion. Investors, too, can look forward to a clearer landscape for capital allocation. The journey to 2.5% will require continued vigilance and adaptability, but the destination promises a more balanced and sustainable global economic environment. The focus now shifts to ensuring this projected stability translates into broad-based prosperity and sustained economic health for all.