Maximizing 529 Plan Benefits 2026: Save 20% on Education Costs
Anúncios
The cost of higher education continues to climb, making strategic financial planning more crucial than ever. For many families, a 529 plan stands as a cornerstone of their college savings strategy. As we look towards 2026, understanding how to maximize your 529 plan benefits is paramount to saving significantly on educational expenses. This comprehensive guide will delve into the nuances of these powerful savings vehicles, offering actionable insights and strategies to help you potentially save 20% or more on college costs.
Anúncios
Understanding the Power of 529 Plans: A Foundation for Savings
A 529 plan is an education savings plan operated by a state or educational institution designed to help families save for future education costs. The primary appeal of 529 plans lies in their tax advantages. Contributions grow tax-deferred, and withdrawals are tax-free when used for qualified education expenses. This dual benefit can lead to substantial savings over time, making them an indispensable tool in your financial arsenal.
The Core Mechanics of a 529 Plan
At its heart, a 529 plan is an investment account. You contribute money, which is then invested in a portfolio of mutual funds, exchange-traded funds (ETFs), or other investment vehicles, similar to a 401(k) or IRA. The key difference is its specific purpose: education. Most states offer two types of 529 plans:
Anúncios
- Education Savings Plans: These are the most common, allowing you to save and invest money for qualified education expenses. The growth is tax-free, and withdrawals for qualified expenses are also tax-free.
- Prepaid Tuition Plans: Less common, these plans allow you to purchase future tuition credits at today’s prices, primarily for in-state public colleges. They offer a hedge against tuition inflation but are less flexible than savings plans.
Why 2026 is a Crucial Year for 529 Planning
While the fundamental structure of 529 plans remains consistent, legislative changes, economic shifts, and evolving educational landscapes can impact their effectiveness. Staying informed about the latest regulations and opportunities for 2026 is vital to fully harness your 529 plan benefits. This includes understanding potential federal tax law adjustments, state-specific incentives, and expanded definitions of qualified expenses.
Strategic Contributions: Fueling Your 529 Plan for Maximum Growth
The more you contribute, and the earlier you start, the more significant the impact of tax-deferred growth. However, simply contributing isn’t enough; strategic contributions can amplify your 529 plan benefits.
Front-Loading Contributions: A Powerful Strategy
One of the most effective strategies for maximizing growth is front-loading your contributions. This involves making a large initial contribution early on. The IRS allows for a special election where you can contribute up to five years’ worth of gift tax exclusion in a single year without incurring gift tax. For 2026, assuming the gift tax exclusion remains at or near current levels, this could mean a significant lump sum contribution, allowing your money more time to grow tax-free.
For example, if the annual gift tax exclusion is $18,000 in 2026, you could contribute $90,000 ($18,000 x 5) per beneficiary in one go. If you and your spouse each contribute, that’s $180,000. This strategy is particularly powerful for grandparents or other relatives looking to make a substantial impact on a child’s education.
Consistency is Key: Regular Contributions
Even if a large lump sum isn’t feasible, consistent, regular contributions are crucial. Setting up automated transfers, even small amounts weekly or monthly, can leverage dollar-cost averaging, reducing the risk of investing a large sum at an market peak and ensuring steady growth over time. The power of compounding interest works wonders when you contribute regularly over many years.
Leveraging State Tax Deductions and Credits
Many states offer tax deductions or credits for 529 plan contributions. These state-specific incentives can significantly boost your 529 plan benefits, effectively reducing the net cost of your contributions. For instance, some states allow you to deduct contributions up to a certain limit from your state taxable income, regardless of which state’s 529 plan you invest in. Other states might only offer a deduction if you contribute to their specific state plan. It’s essential to research your state’s particular rules for 2026 to ensure you’re taking full advantage of these benefits.
Understanding Qualified Expenses in 2026: Beyond Tuition
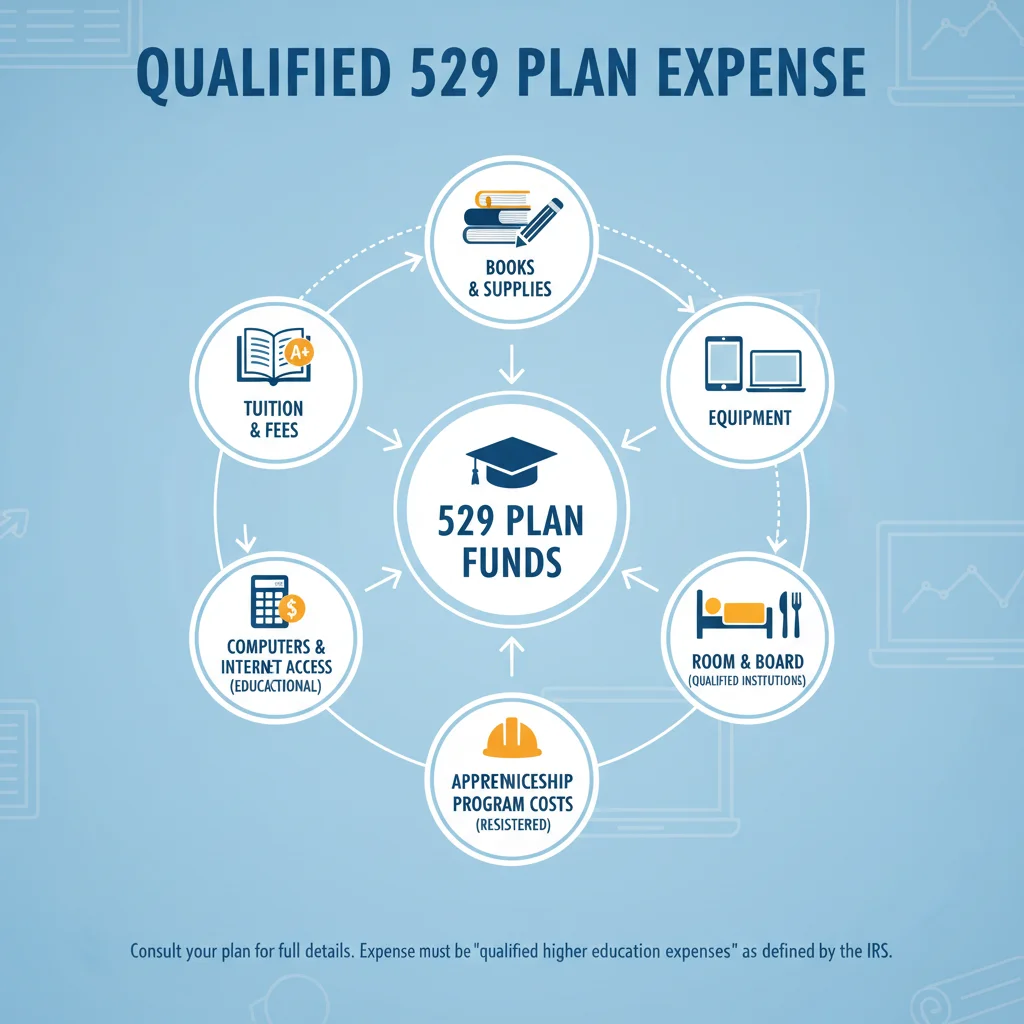
One of the most common misconceptions about 529 plans is that they only cover tuition. While tuition is a primary expense, the definition of "qualified education expenses" has expanded significantly over the years, offering more flexibility and increasing the overall 529 plan benefits.
Traditional Qualified Expenses
For eligible educational institutions (accredited post-secondary schools, including universities, colleges, and vocational schools), qualified expenses include:
- Tuition and Fees: The most straightforward use of 529 funds.
- Books, Supplies, and Equipment: This includes textbooks, course materials, lab equipment, and even computers and internet access if required for enrollment.
- Room and Board: For students enrolled at least half-time, this includes the cost of living on or off-campus, up to the amount determined by the institution for federal financial aid purposes.
Expanded Qualified Expenses for 2026
Recent legislative changes have broadened the scope of qualified expenses, making 529 plans even more versatile:
- K-12 Tuition: Up to $10,000 per year per student can be used for tuition expenses at public, private, or religious elementary or secondary schools. This provides significant relief for families with children in private K-12 education.
- Apprenticeship Programs: Expenses for fees, books, supplies, and equipment required for participation in a registered apprenticeship program are now qualified. This opens up 529 plans to a wider range of career paths.
- Student Loan Repayment: A lifetime maximum of $10,000 per beneficiary (and an additional $10,000 for each of the beneficiary’s siblings) can be used to repay qualified student loans. This is a game-changer for graduates burdened by student debt.
- Rollover to Roth IRA: Starting in 2024, if a 529 account has been open for at least 15 years, and there have been no contributions to the account for the last five years, up to $35,000 can be rolled over tax-free from a 529 plan to a Roth IRA for the beneficiary. This provides an excellent fallback option if the beneficiary doesn’t use all the funds for education. While this is already in effect, understanding its implications for long-term planning into 2026 is crucial.
Staying updated on these expanded qualified expenses ensures you’re maximizing every aspect of your 529 plan benefits. Before making any withdrawals, always verify the current IRS guidelines and state-specific rules.
Investment Strategies Within Your 529 Plan for Optimal Returns
The investment options within 529 plans are crucial for growth. Most plans offer a variety of portfolios, from aggressive to conservative, often including age-based options that automatically adjust risk as the beneficiary approaches college age.
Age-Based Portfolios: Set It and Forget It
For many, age-based portfolios are an excellent choice. These portfolios automatically shift from more aggressive investments (like stocks) to more conservative ones (like bonds and cash) as the beneficiary gets closer to needing the funds. This de-risking strategy helps protect accumulated savings from market downturns just before college enrollment. This is a primary way to secure your 529 plan benefits against market volatility.
Static Portfolios: More Control, More Responsibility
For those comfortable with managing their investments, static portfolios offer more control. You choose a specific asset allocation and maintain it, rebalancing as needed. This requires more active management but can potentially lead to higher returns if managed effectively. However, it also carries higher risk.
Reviewing and Rebalancing Your Portfolio
It’s advisable to review your 529 plan’s investment performance annually, or whenever there are significant market changes. While age-based portfolios rebalance automatically, those with static portfolios will need to do it manually. Even with age-based portfolios, understanding their underlying investments and ensuring they align with your risk tolerance is good practice. You are generally allowed to change your investment options twice per calendar year, or when you change the beneficiary.
Navigating the Tax Landscape: Federal and State Benefits
The tax advantages are the cornerstone of 529 plan benefits. Understanding these can significantly reduce your overall education costs.
Federal Tax Benefits
Federally, 529 plan contributions are not tax-deductible. However, the growth of your investments is tax-deferred, and qualified withdrawals are entirely tax-free. This means you won’t pay federal income tax on any earnings, which can be a substantial sum over 10-18 years of saving.
State Tax Benefits
As mentioned earlier, many states offer tax incentives for 529 plan contributions. These can include:
- State Income Tax Deductions: A direct reduction in your taxable income for contributions made.
- State Tax Credits: A direct reduction in the amount of tax you owe, which is even more valuable than a deduction.
The rules vary widely by state. Some states offer deductions for contributions to any state’s 529 plan, while others only offer incentives for contributions to their own state’s plan. Some states have no income tax, so no deduction is available. It’s crucial to consult your state’s tax laws or a tax professional to understand the specific 529 plan benefits available in your location for 2026.
Gift Tax Considerations
Contributions to a 529 plan are considered gifts for tax purposes. However, they qualify for the annual gift tax exclusion. For 2026, this exclusion amount is expected to be around $18,000 per donor per beneficiary. As discussed, you can also elect to treat a lump sum contribution of up to five times the annual exclusion as if it were spread out over five years, allowing for significant initial funding without gift tax implications. This is a powerful tool for maximizing your 529 plan benefits from the outset.
Flexibility and Control: Adapting to Life’s Changes
One of the often-overlooked aspects of 529 plans is their flexibility. Life rarely goes exactly as planned, and 529 plans are designed to adapt.
Changing Beneficiaries
If the original beneficiary decides not to pursue higher education, or if there are leftover funds, you can change the beneficiary to another eligible family member without tax penalty. Eligible family members include siblings, first cousins, nieces, nephews, and even the account owner themselves. This flexibility ensures that your saved funds can still be used for educational purposes within your family, preserving your 529 plan benefits.
Transferring Funds
You can also transfer funds between different 529 plans for the same beneficiary (once every 12 months) or to a different beneficiary. This can be useful if you find a plan in another state with better investment options or lower fees.
What if the Beneficiary Doesn’t Go to College?
This is a common concern. As mentioned, the rollover to a Roth IRA is a fantastic new option. Other alternatives include:
- Changing the Beneficiary: Assign the funds to another family member.
- Paying for Other Qualified Expenses: Use the funds for K-12 tuition, apprenticeship programs, or student loan repayment.
- Non-Qualified Withdrawals: You can always withdraw funds for non-qualified expenses. However, the earnings portion of the withdrawal will be subject to federal income tax and a 10% federal penalty tax. The principal contributions are returned tax-free. While not ideal, it’s an option if all else fails.
The Intersection of 529 Plans and Financial Aid
Many families worry that saving in a 529 plan will negatively impact their eligibility for financial aid. While it’s true that 529 assets are considered in financial aid calculations, their impact is generally minimal compared to other asset types.
Parent-Owned 529 Plans
When a 529 plan is owned by a dependent student’s parent, it’s considered a parental asset on the Free Application for Federal Student Aid (FAFSA). Parental assets are assessed at a maximum rate of 5.64%. This means that for every $10,000 saved in a parent-owned 529 plan, the student’s financial aid eligibility might be reduced by only $564. This is a much lower assessment rate than student-owned assets or income.
Grandparent-Owned 529 Plans
Previously, grandparent-owned 529 plans had a more significant impact on financial aid because withdrawals were counted as untaxed income to the student, assessed at a rate of up to 50%. However, recent FAFSA Simplification Act changes have largely eliminated this issue. Starting with the 2024-2025 FAFSA (relevant for students attending college in 2026-2027), cash support from grandparents (including 529 distributions) is no longer required to be reported as student income. This makes grandparent-owned 529 plans an even more attractive option for maximizing 529 plan benefits without heavily penalizing financial aid.
Working with a Financial Advisor
Given the complexities of financial aid formulas and the ever-changing legislative landscape, consulting with a financial advisor specializing in college planning can be invaluable. They can help you strategize the optimal way to save, withdraw, and manage your 529 funds to maximize both your 529 plan benefits and potential financial aid.
Advanced Strategies for Maximizing 529 Plan Benefits in 2026
Beyond the basics, several advanced strategies can further enhance your 529 plan benefits.
Superfunding Contributions
We touched on this earlier, but it’s worth emphasizing. "Superfunding" involves making a lump-sum contribution that exceeds the annual gift tax exclusion by utilizing the five-year election. This strategy is particularly powerful for those with substantial funds available, allowing for maximum tax-free growth over the longest possible time horizon.
Changing Account Ownership
In some cases, changing the account owner might be beneficial, particularly for financial aid purposes or if the original owner passes away. While generally straightforward, it’s important to understand the implications, especially regarding state tax benefits and control over the funds. Consult with your plan administrator and a tax professional before initiating an ownership change.
Using 529 Plans for Multiple Beneficiaries
If you have multiple children, you can open a separate 529 plan for each, or some plans allow you to designate multiple beneficiaries. The flexibility to change beneficiaries means that if one child receives a scholarship or doesn’t attend college, the funds can be reallocated to another child, ensuring the 529 plan benefits stay within the family.
Combining 529 Plans with Other Savings Vehicles
While 529 plans are powerful, they don’t have to be your only savings tool. Combining them with Coverdell Education Savings Accounts (ESAs), Roth IRAs (which can also be used for education expenses without penalty if certain conditions are met), and even taxable investment accounts can create a robust, multi-faceted education funding strategy. Each vehicle has its own advantages and disadvantages, and a diversified approach can offer greater flexibility and tax efficiency.
Common Pitfalls to Avoid When Using 529 Plans
To truly maximize your 529 plan benefits, it’s equally important to be aware of potential pitfalls.
Non-Qualified Withdrawals
As discussed, using 529 funds for non-qualified expenses will result in the earnings portion being taxed as ordinary income and subject to a 10% federal penalty. Be meticulous about what constitutes a qualified expense.
Over-Saving
While less common, it is possible to over-save in a 529 plan, especially with the generous contribution limits (often over $500,000 per beneficiary). If a beneficiary receives significant scholarships or decides not to pursue higher education, you might be left with excess funds. The new Roth IRA rollover option significantly mitigates this risk, but it’s still worth considering. Diversifying your savings across multiple vehicles can help manage this risk.
Ignoring State-Specific Rules
Each state’s 529 plan has its own rules, fees, and investment options. While you can invest in any state’s plan, you might miss out on state tax benefits if you don’t choose your home state’s plan (or another state’s plan that offers benefits to your residents). Always research and compare plans before committing.
Not Reviewing Your Plan Regularly
Market conditions change, educational costs fluctuate, and your financial situation evolves. Failing to review your 529 plan periodically can lead to missed opportunities or an investment strategy that no longer aligns with your goals. Annual reviews are highly recommended.
The Future of 529 Plans and What to Expect in 2026 and Beyond
The landscape of education finance is constantly evolving. While 529 plans have proven to be resilient and adaptable, it’s wise to consider potential future changes.
Potential Legislative Adjustments
Congress periodically reviews and revises tax laws. While 529 plans have broad bipartisan support, minor adjustments to contribution limits, qualified expenses, or tax treatment are always possible. Staying informed through reputable financial news sources and consulting with advisors will help you adapt to any new regulations.
Inflation and Investment Performance
Inflation continues to be a concern, especially in the education sector. Your 529 plan’s investment performance needs to outpace inflation to truly maximize your 529 plan benefits. Regularly assessing your portfolio’s returns against educational inflation rates is crucial.
The Evolving Definition of "Education"
As the job market changes, so does the nature of education. The inclusion of apprenticeship programs as qualified expenses is a testament to this evolution. It’s possible that in the future, other forms of career training or lifelong learning initiatives might also become eligible, further broadening the utility of 529 plans.
Conclusion: Your Path to Significant Educational Savings
Maximizing your 529 plan benefits in 2026 is about more than just opening an account; it’s about strategic planning, consistent contributions, informed investment choices, and a thorough understanding of the ever-expanding list of qualified expenses and tax advantages. By leveraging front-loading strategies, understanding state-specific incentives, utilizing expanded qualified expenses like K-12 tuition and student loan repayment, and adapting to new options like the Roth IRA rollover, families can significantly reduce the financial burden of education.
With careful planning and ongoing diligence, a 529 plan can be one of the most powerful tools in your financial toolkit, helping you save 20% or more on educational costs and secure a brighter future for your loved ones. Don’t let the complexities deter you; the potential savings are well worth the effort. Start planning today to ensure you’re fully prepared for the educational expenses of tomorrow.