2026 Capital Gains Tax Adjustments: Save 7% Annually
Anúncios
Understanding the 2026 Capital Gains Tax adjustments is crucial for investors aiming to optimize their portfolios and potentially save a significant 7% annually on their investments through strategic planning.
Anúncios
For investors in the United States, navigating the evolving landscape of tax legislation is paramount for maximizing returns and minimizing liabilities. The impending 2026 Capital Gains Tax adjustments represent a significant shift, offering both challenges and opportunities. This comprehensive guide is designed to equip you with the knowledge and strategies necessary to understand these changes and potentially save up to 7% annually on your investments.
Anúncios
The Impending Shift: What to Expect from 2026 Capital Gains Tax
The year 2026 is poised to bring notable changes to how capital gains are taxed in the United States. These adjustments are part of broader fiscal policies aimed at recalibrating the economic landscape. Investors must be proactive in understanding these modifications to ensure their portfolios remain optimized and compliant with new regulations.
Historically, capital gains tax rates have been subject to legislative review and modification. The 2026 adjustments are expected to introduce new thresholds and possibly alter the rates applied to both short-term and long-term capital gains. Staying informed about these specific changes is the first step toward effective financial planning and maximizing your after-tax returns.
Understanding the Difference: Short-Term vs. Long-Term Gains
A fundamental aspect of capital gains taxation revolves around the holding period of an asset. Differentiating between short-term and long-term gains is crucial because they are taxed at different rates.
- Short-Term Capital Gains: These apply to assets held for one year or less. They are typically taxed at ordinary income tax rates, which can be significantly higher than long-term rates.
- Long-Term Capital Gains: These apply to assets held for more than one year. Historically, these rates have been more favorable, often set at 0%, 15%, or 20% depending on an individual’s taxable income.
- Anticipated 2026 Changes: While specific figures are still subject to final legislation, experts anticipate potential adjustments to these rate tiers, possibly impacting how much income falls into each bracket.
The distinction between these two categories will continue to play a pivotal role in tax planning. Investors should carefully consider their holding periods when making investment decisions, especially as 2026 approaches. Understanding these nuances can help in strategically timing sales to fall into more favorable tax categories, thereby reducing your overall tax burden.
Strategic Asset Allocation for Reduced Tax Liability
Effective asset allocation goes beyond merely balancing risk and return; it also involves optimizing for tax efficiency. With the 2026 capital gains tax adjustments on the horizon, a strategic review of your asset allocation can significantly impact your annual tax savings.
Consider placing income-generating assets, such as bonds or real estate investment trusts (REITs), in tax-advantaged accounts like IRAs or 401(k)s. This strategy shelters the income and capital gains from immediate taxation, allowing for greater compounding growth. Growth-oriented investments, like certain stocks that you plan to hold for the long term, might be better suited for taxable accounts where they can benefit from lower long-term capital gains rates.
Tax-Loss Harvesting: A Timeless Strategy
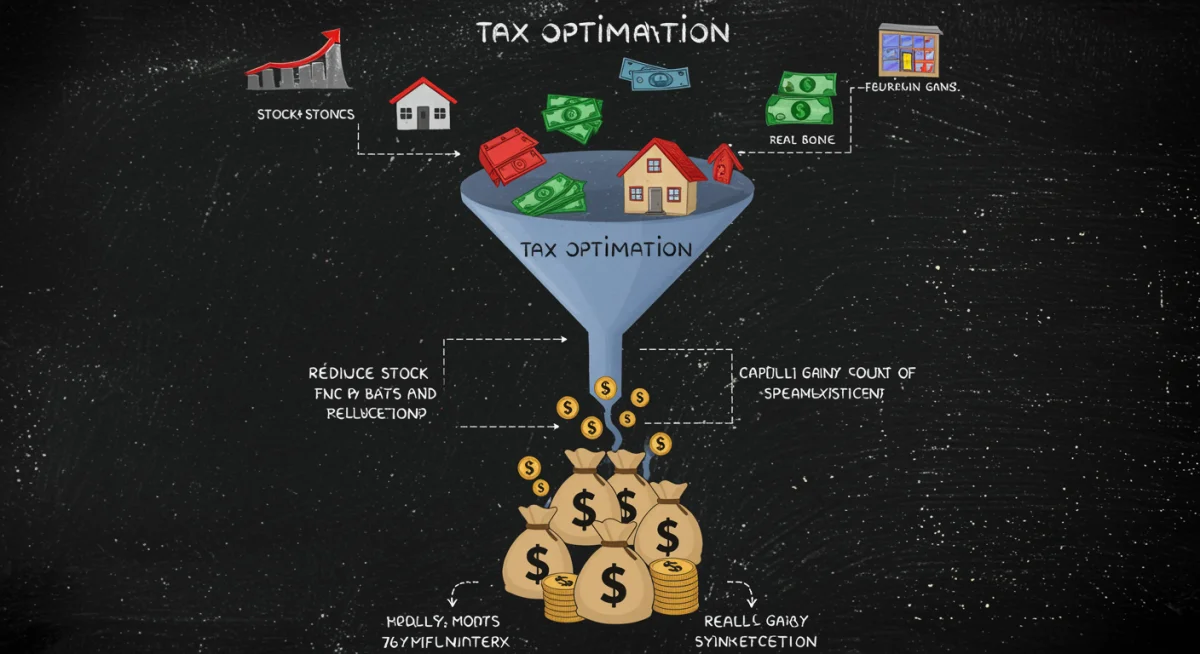
Tax-loss harvesting remains one of the most powerful tools in an investor’s arsenal, and its importance is amplified with impending tax changes. This strategy involves selling investments at a loss to offset capital gains and, potentially, a limited amount of ordinary income.
- Offsetting Gains: Losses can first be used to offset any capital gains you’ve realized during the year.
- Offsetting Income: If your capital losses exceed your capital gains, you can use up to $3,000 of the remaining loss to offset ordinary income each year. Any unused losses can be carried forward indefinitely to future tax years.
- Proactive Planning: With 2026 in mind, review your portfolio for underperforming assets that could be sold to generate losses. This can help mitigate the impact of potential higher capital gains rates on your profitable investments.
Implementing a consistent tax-loss harvesting strategy, especially in years leading up to significant tax changes, can provide a buffer against increased tax liabilities. It’s a proactive measure that can result in substantial annual savings, aligning with the goal of saving 7% or more on your capital gains.
Leveraging Tax-Advantaged Accounts Before 2026
Tax-advantaged accounts are critical components of a well-rounded investment strategy, offering shelters against current and future tax liabilities. As we approach 2026, maximizing your contributions to these accounts becomes even more crucial for preserving wealth and optimizing tax efficiency.
Accounts such as 401(k)s, IRAs (Traditional and Roth), and Health Savings Accounts (HSAs) provide various tax benefits, from tax-deductible contributions to tax-free growth and withdrawals. Understanding the nuances of each and how they can shield your capital gains from the anticipated 2026 adjustments is key.
Individual Retirement Accounts (IRAs) and 401(k)s
These retirement vehicles offer significant tax benefits that can help mitigate the impact of capital gains taxes. Traditional IRAs and 401(k)s allow for pre-tax contributions, meaning your contributions reduce your taxable income in the present. Investments within these accounts grow tax-deferred, and you only pay taxes upon withdrawal in retirement. Roth IRAs, on the other hand, are funded with after-tax dollars, but qualified withdrawals in retirement are entirely tax-free, including all capital gains.
- Contribution Limits: Be aware of the annual contribution limits for each account type and strive to contribute the maximum allowed if feasible.
- Catch-Up Contributions: If you are aged 50 or older, you may be eligible to make additional catch-up contributions, further boosting your tax-advantaged savings.
- Diversification: Utilize these accounts to hold a diversified portfolio, placing assets that are expected to generate significant capital gains within Roth accounts for tax-free growth.
By strategically funding and managing your IRA and 401(k) accounts, you can effectively shield a portion of your investment gains from the 2026 tax changes, ensuring more of your investment growth remains in your pocket.
Understanding Qualified Dividends and Capital Gains
The distinction between ordinary dividends and qualified dividends, as well as their relationship with capital gains, is an important area for investors to grasp, especially with potential tax changes. Qualified dividends are taxed at the same preferential rates as long-term capital gains, which can be significantly lower than ordinary income tax rates.
To qualify, dividends must meet specific criteria, including being paid by a U.S. corporation or a qualified foreign corporation, and the stock must be held for a certain minimum period. Understanding these rules allows investors to structure their portfolios to generate more tax-efficient income.
Optimizing Dividend-Paying Investments
When selecting dividend-paying stocks, consider those that historically pay qualified dividends. This can substantially reduce the tax burden on your investment income. The holding period rule is critical here; rushing to sell a stock before it meets the qualified dividend holding period could convert a tax-advantaged gain into a less favorable one.
- Research: Investigate a company’s dividend history and tax treatment before investing. Many brokerage platforms provide this information.
- Holding Period: Be mindful of the required holding period for qualified dividends. Selling too soon can negate the tax benefits.
- Reinvesting: Consider reinvesting qualified dividends within a tax-advantaged account to allow for tax-deferred or tax-free compounding growth.
By focusing on qualified dividends and understanding their tax implications, investors can enhance their after-tax returns, contributing to the overall goal of saving 7% annually on their investments. This strategy, combined with careful capital gains planning, creates a robust framework for tax efficiency.
Advanced Strategies: Charitable Giving and Opportunity Zones
Beyond traditional tax planning, advanced strategies like charitable giving and investing in Opportunity Zones offer unique avenues for reducing capital gains tax liabilities. These approaches not only provide financial benefits but can also align with philanthropic goals or contribute to economic development.
Charitable giving, when structured correctly, can allow investors to donate appreciated assets, avoiding capital gains tax on the appreciation while also receiving a charitable deduction. Opportunity Zones, a more recent initiative, offer significant tax incentives for investing in designated low-income communities.
Donating Appreciated Assets to Charity
Instead of selling appreciated stock or other assets and then donating the cash, consider donating the assets directly to a qualified charity. When you donate appreciated property held for more than one year, you generally avoid paying capital gains tax on the appreciated value. Additionally, you can typically deduct the fair market value of the property, subject to certain limitations.
- Direct Donation: This circumvents the need to sell assets, thereby avoiding capital gains tax on the appreciation.
- Tax Deduction: You receive a deduction for the fair market value, potentially reducing your ordinary income tax.
- Strategic Timing: Consider this strategy, especially for highly appreciated assets that you might otherwise sell, particularly in years leading up to or during the 2026 tax changes.
This strategy offers a win-win situation, allowing you to support causes you care about while significantly reducing your tax burden. It’s a powerful tool for investors with substantial appreciated assets.
Staying Informed and Adapting Your Portfolio
The tax landscape is dynamic, and staying informed about legislative developments is crucial for effective investment management. The 2026 capital gains tax adjustments underscore the need for continuous vigilance and adaptability in your financial planning. Relying on outdated information can lead to missed opportunities or unexpected tax liabilities.
Regularly consulting with financial advisors and tax professionals is an indispensable part of this process. They can provide personalized advice tailored to your specific financial situation and help you navigate the complexities of tax law.
The Role of Financial Advisors and Tax Professionals
A qualified financial advisor can help you review your investment portfolio, assess potential tax impacts, and recommend strategies to optimize your returns. Tax professionals, such as CPAs, specialize in interpreting tax laws and ensuring your compliance while maximizing deductions and credits.
- Personalized Guidance: Advisors can offer insights specific to your income, assets, and financial goals.
- Tax Law Interpretation: Professionals stay abreast of legislative changes and can explain how they apply to you.
- Proactive Planning: They can help you implement strategies like tax-loss harvesting, asset location, and charitable giving effectively.
By maintaining an open dialogue with your financial and tax advisors, you can ensure your investment strategy remains agile and responsive to regulatory shifts. This proactive approach is key to achieving your financial goals and saving that crucial 7% annually, even amidst evolving tax conditions.
| Key Strategy | Benefit for 2026 |
|---|---|
| Tax-Loss Harvesting | Offset capital gains and up to $3,000 of ordinary income annually. |
| Tax-Advantaged Accounts | Shield investments from current and future capital gains taxes (e.g., IRAs, 401(k)s). |
| Qualified Dividends | Receive preferential tax rates similar to long-term capital gains, reducing income tax. |
| Charitable Giving | Avoid capital gains on appreciated assets and receive a tax deduction. |
Frequently Asked Questions About 2026 Capital Gains Tax
The 2026 Capital Gains Tax adjustments are anticipated to include modifications to tax rate tiers for both short-term and long-term gains, alongside potential changes to income thresholds. These changes aim to recalibrate the tax system, impacting how investment profits are taxed for individuals and corporations.
Saving 7% annually can be achieved through strategic planning, including maximizing contributions to tax-advantaged accounts like 401(k)s and IRAs, implementing tax-loss harvesting, optimizing asset allocation, and focusing on qualified dividend-paying investments. Consulting a financial advisor is recommended for tailored strategies.
Yes, the distinction between short-term (assets held one year or less) and long-term (assets held over one year) capital gains will remain. Short-term gains will likely continue to be taxed at ordinary income rates, while long-term gains will benefit from preferential, lower rates, though the specific tiers may shift.
Tax-advantaged accounts such as IRAs, 401(k)s, and HSAs are crucial. They shield investments from immediate taxation, allowing for tax-deferred or tax-free growth and withdrawals, depending on the account type. Maximizing contributions to these accounts helps mitigate the impact of capital gains tax adjustments.
It’s advisable to review and potentially adjust your portfolio. Consider rebalancing, optimizing asset location, and exploring strategies like charitable giving of appreciated assets. Proactive planning with a financial expert can help you adapt to the 2026 changes and maintain tax efficiency.
Conclusion
The upcoming 2026 Capital Gains Tax adjustments underscore the importance of proactive and informed financial planning for every investor. While changes can sometimes seem daunting, they often present opportunities for those who are prepared. By understanding the nuances of short-term versus long-term gains, leveraging tax-advantaged accounts, employing strategies like tax-loss harvesting, and utilizing advanced techniques such as charitable giving, investors can not only navigate these changes successfully but also potentially realize significant annual savings of up to 7%. Engaging with qualified financial and tax professionals is paramount to tailoring these strategies to your unique financial situation, ensuring your portfolio remains resilient and optimized for future growth.