Unlock 2026 Tax Savings: Maximizing Deductions with Latest IRS Updates
Anúncios
Unlock 2026 Tax Savings: Maximizing Deductions with the Latest IRS Updates for the Upcoming Filing Season
As the calendar pages turn, savvy individuals and businesses are already looking ahead to the 2026 tax season. Proactive tax planning is not merely a suggestion; it’s a critical strategy for maximizing your financial well-being. Understanding the evolving landscape of IRS regulations, potential new tax laws, and available deductions is paramount to achieving significant 2026 Tax Savings. This comprehensive guide will delve into the anticipated changes, highlight key strategies, and provide actionable insights to help you navigate the complexities of the upcoming filing season.
Anúncios
The Internal Revenue Service (IRS) continually updates its guidelines, and staying informed is the first step toward optimizing your tax position. While specific legislative changes for 2026 are still taking shape, we can anticipate certain trends and areas of focus based on current economic conditions and ongoing policy discussions. By preparing now, you can position yourself to take full advantage of every opportunity to reduce your tax liability and enhance your overall financial health.
Understanding the Foundation of 2026 Tax Savings: Key IRS Updates and Potential Changes
The foundation of effective 2026 Tax Savings lies in a deep understanding of the prevailing tax code and any forthcoming adjustments. While the Tax Cuts and Jobs Act (TCJA) of 2017 brought significant changes, many of its provisions are set to expire or change by the end of 2025, directly impacting the 2026 tax year. This means taxpayers could see shifts in individual income tax rates, standard deductions, and various other credits and deductions.
Anúncios
One of the most significant areas to watch is the potential expiration of certain TCJA provisions. For instance, individual income tax rates are scheduled to revert to their pre-TCJA levels, which could mean higher rates for many taxpayers. Similarly, the increased standard deduction amounts may decrease, making itemizing deductions more attractive for a broader group of people. Other changes could include adjustments to the child tax credit, limitations on state and local tax (SALT) deductions, and modifications to estate tax exemptions. Keeping an eye on these potential shifts will be crucial for strategic planning.
Beyond the scheduled expirations, new legislation could also be introduced and passed that impacts the 2026 tax year. Economic conditions, political priorities, and social needs often drive new tax policies. For example, there could be new incentives for certain types of investments, energy-efficient home improvements, or specific industry support. Conversely, there might be new taxes or limitations on existing deductions to fund government initiatives. Subscribing to IRS news alerts, consulting with tax professionals, and following reputable financial news sources are excellent ways to stay abreast of these developments.
Furthermore, the IRS continues to modernize its operations, including digital services and enforcement priorities. Taxpayers should anticipate ongoing efforts to improve tax compliance through data analytics and technology. This means accurate record-keeping and diligent reporting will remain paramount. Understanding these foundational elements is the first step toward unlocking substantial 2026 Tax Savings.
Strategic Deductions: Your Pathway to Maximizing 2026 Tax Savings
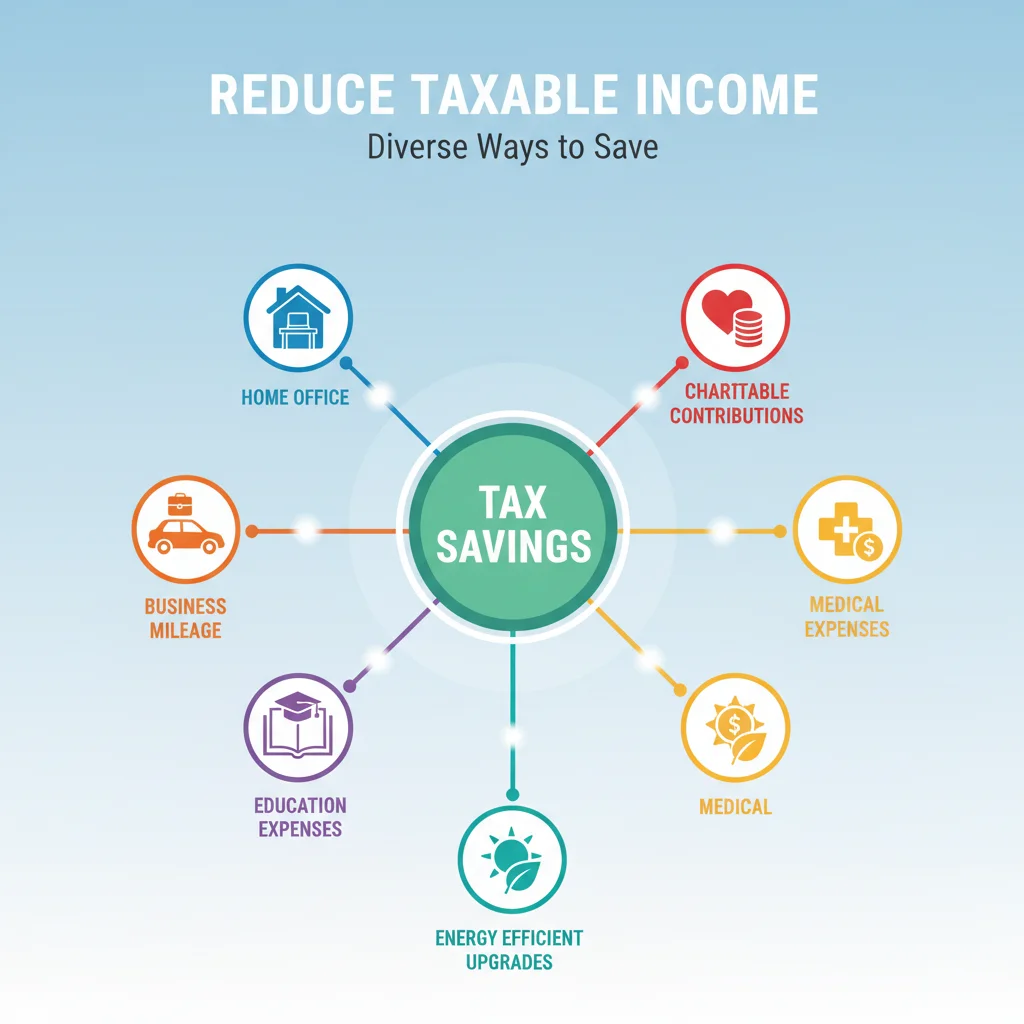
Maximizing 2026 Tax Savings heavily relies on effectively utilizing available deductions. Deductions reduce your taxable income, thereby lowering your overall tax bill. It’s essential to not only be aware of common deductions but also to understand how potential changes in 2026 might alter their impact or eligibility.
Itemized vs. Standard Deduction: Re-evaluating Your Choice
With the potential decrease in the standard deduction amounts post-TCJA, more taxpayers might find it advantageous to itemize their deductions in 2026. Common itemized deductions include:
- State and Local Taxes (SALT): The current $10,000 cap on SALT deductions is a significant point of contention. If this cap is adjusted or removed, it could provide substantial savings, especially for homeowners in high-tax states.
- Mortgage Interest: Interest paid on home mortgages remains a key deduction for many homeowners. Understanding the limits and eligibility criteria is vital.
- Charitable Contributions: Donations to qualified charities can be deducted. Keep meticulous records of all contributions, both cash and non-cash.
- Medical Expenses: If your unreimbursed medical expenses exceed 7.5% of your adjusted gross income (AGI), you can deduct the amount exceeding this threshold.
It’s crucial to track all potential itemized expenses throughout the year. Even small amounts can add up, and with a potentially lower standard deduction, itemizing might become your preferred strategy for 2026 Tax Savings.
Above-the-Line Deductions: Reducing Your AGI
Above-the-line deductions are particularly valuable because they reduce your Adjusted Gross Income (AGI), which can then impact your eligibility for other credits and deductions. These include:
- IRA Contributions: Contributions to a traditional IRA are often tax-deductible, up to certain limits. This is a powerful tool for both retirement savings and immediate tax relief.
- Health Savings Account (HSA) Contributions: If you have a high-deductible health plan (HDHP), contributions to an HSA are tax-deductible, and withdrawals for qualified medical expenses are tax-free.
- Student Loan Interest: You can deduct a limited amount of student loan interest paid during the year.
- Self-Employment Tax: Self-employed individuals can deduct one-half of their self-employment taxes.
Maximizing these deductions proactively throughout 2026 can significantly lower your AGI, leading to greater 2026 Tax Savings.
Business Deductions: A Cornerstone of 2026 Tax Savings for Entrepreneurs
For business owners and self-employed individuals, understanding and utilizing business deductions is a cornerstone of achieving substantial 2026 Tax Savings. The tax code offers numerous opportunities to reduce taxable business income, but accurate record-keeping and adherence to IRS guidelines are critical.
Common Business Deductions to Leverage:
- Qualified Business Income (QBI) Deduction: The Section 199A QBI deduction allows eligible self-employed and small business owners to deduct up to 20% of their qualified business income. While this deduction is also subject to potential changes post-TCJA, it remains a significant area to monitor.
- Home Office Deduction: If you use a portion of your home exclusively and regularly for business, you may qualify for the home office deduction. This can be calculated using the simplified option or the regular method, which involves actual expenses.
- Business Expenses: Almost all ordinary and necessary business expenses are deductible. This includes rent, utilities, office supplies, software, professional development, and travel expenses. Keep detailed records and receipts for all expenditures.
- Depreciation: Businesses can deduct the cost of assets over their useful life through depreciation. Section 179 expensing and bonus depreciation allow for accelerated deductions, which can provide immediate tax relief. Monitor any changes to these provisions for 2026.
- Employee Benefits: Costs associated with employee wages, health insurance, and retirement plans are generally deductible.
Planning for Capital Expenditures and Investments:
Strategic timing of capital expenditures can also impact 2026 Tax Savings. If you anticipate purchasing significant equipment or making substantial investments in your business, understanding the depreciation rules and potential bonus depreciation rates for 2026 will be crucial. These deductions can significantly offset income in the year of purchase or over several years.
Furthermore, businesses should consider tax credits for research and development (R&D), hiring specific employee groups, or investing in certain energy-efficient technologies. These credits directly reduce your tax liability dollar-for-dollar, making them incredibly valuable for maximizing 2026 Tax Savings.
Retirement Planning: A Dual Approach to 2026 Tax Savings
Retirement planning is not just about saving for the future; it’s also a powerful tool for achieving current 2026 Tax Savings. The tax code provides numerous incentives for individuals to save for retirement, offering immediate deductions or tax-deferred growth.
Traditional IRAs and 401(k)s:
Contributions to traditional IRAs and 401(k)s are typically tax-deductible in the year they are made, up to annual limits. For many, maximizing these contributions is one of the easiest ways to reduce taxable income. The limits for 2026 will likely be announced later, but planning to contribute the maximum amount should be a priority. Catch-up contributions for those aged 50 and over provide an additional opportunity to save and deduct more.
Roth IRAs and 401(k)s:
While Roth contributions are not tax-deductible, they offer tax-free withdrawals in retirement, which can be a significant advantage, especially if you anticipate being in a higher tax bracket later in life. Understanding the income limitations for Roth IRA contributions and considering a Roth conversion strategy (which can have immediate tax implications but long-term benefits) are important aspects of comprehensive tax planning.
Self-Employed Retirement Plans: SEP IRAs and Solo 401(k)s:
Self-employed individuals have access to powerful retirement vehicles like SEP IRAs and Solo 401(k)s, which allow for much higher contribution limits than traditional IRAs. These plans provide substantial deductions for business owners, directly contributing to significant 2026 Tax Savings while building a robust retirement nest egg.
Consulting with a financial advisor can help you determine the most suitable retirement plan for your specific situation, ensuring you maximize both your retirement savings and your immediate tax benefits.
Education Tax Credits and Deductions: Investing in Knowledge, Saving on Taxes
Education expenses can be substantial, but the IRS offers several tax credits and deductions to help offset these costs, contributing to your 2026 Tax Savings. These provisions are designed to make higher education more accessible and affordable.
American Opportunity Tax Credit (AOTC):
The AOTC is a partially refundable credit worth up to $2,500 per eligible student for the first four years of post-secondary education. To qualify, the student must be pursuing a degree or other recognized educational credential and be enrolled at least half-time for at least one academic period beginning in the tax year. This credit is particularly valuable as up to 40% of it is refundable, meaning you could get up to $1,000 back even if you don’t owe any tax.
Lifetime Learning Credit (LLC):
The LLC is a non-refundable credit worth up to $2,000 per tax return for qualified education expenses. It’s available for undergraduate, graduate, and professional degree courses, as well as courses taken to acquire job skills. Unlike the AOTC, there’s no limit on the number of years you can claim the LLC, making it ideal for lifelong learners or those pursuing advanced degrees.
Student Loan Interest Deduction:
As mentioned earlier, you can deduct up to $2,500 in student loan interest paid during the year. This is an above-the-line deduction, meaning it reduces your AGI. This deduction can be claimed even if you don’t itemize.
Other Education-Related Deductions:
While tuition and fees deduction has historically been available, its status for 2026 will depend on legislative action. Additionally, if you are self-employed and take courses to maintain or improve skills needed for your current job, those education expenses might be deductible as business expenses. Careful planning and record-keeping of all education-related costs are essential to fully leverage these opportunities for 2026 Tax Savings.
Beyond Deductions: Tax Credits and Other Strategies for 2026 Tax Savings
While deductions reduce your taxable income, tax credits directly reduce your tax liability dollar-for-dollar, making them incredibly powerful tools for 2026 Tax Savings. Understanding available credits and other strategic moves is crucial for a holistic tax plan.
Key Tax Credits to Consider:
- Child Tax Credit (CTC): The CTC was significantly expanded under the American Rescue Plan, but those expansions largely expired. For 2026, the credit amount and refundability will depend on whether Congress extends or modifies existing provisions. It’s a critical area to monitor for families.
- Earned Income Tax Credit (EITC): This refundable credit helps low-to moderate-income working individuals and families. The amount depends on your income, filing status, and number of qualifying children.
- Child and Dependent Care Credit: If you pay for childcare so you can work or look for work, you might be eligible for this credit. Like the CTC, its specific parameters for 2026 will be subject to ongoing legislative decisions.
- Residential Energy Credits: Credits for installing energy-efficient home improvements (like solar panels, energy-efficient windows, or heat pumps) can provide significant savings. These credits have seen recent enhancements and are likely to continue as part of environmental initiatives.
- Premium Tax Credit: If you purchased health insurance through a state or federal marketplace and meet income requirements, you might qualify for this credit.
Other Strategic Moves for 2026 Tax Savings:
- Tax Loss Harvesting: If you have investments, consider selling investments at a loss to offset capital gains and potentially a limited amount of ordinary income. This strategy is particularly effective in volatile markets.
- Gifting Strategies: Utilize the annual gift tax exclusion to transfer wealth to others without incurring gift tax. This can be a part of a broader estate planning strategy.
- Tax-Efficient Investing: Prioritize holding income-generating investments in tax-advantaged accounts (like 401(k)s or IRAs) and growth-oriented investments in taxable accounts to manage capital gains more effectively.
- Flexible Spending Accounts (FSAs) and Health Savings Accounts (HSAs): Maximizing contributions to these accounts allows you to pay for healthcare expenses with pre-tax dollars, reducing your taxable income.
Each of these strategies, when carefully integrated into your financial plan, can amplify your 2026 Tax Savings. It’s not just about finding one big deduction, but rather combining multiple smaller advantages for a cumulative impact.
The Importance of Professional Guidance for 2026 Tax Savings
While this guide provides a comprehensive overview, the nuances of tax law and individual financial situations necessitate professional guidance. The landscape of tax regulations is constantly shifting, and what applies to one taxpayer may not apply to another. Seeking advice from a qualified tax professional or financial advisor is arguably the most crucial step in ensuring you maximize your 2026 Tax Savings.
A tax professional can:
- Interpret Complex Laws: They stay updated on all IRS changes, legislative developments, and court rulings that could impact your taxes.
- Identify Missed Opportunities: An expert can uncover deductions and credits you might overlook, tailored to your specific income, expenses, and family situation.
- Strategize for Future Savings: Beyond the current year, they can help you plan for long-term tax efficiency, including retirement, investments, and estate planning.
- Ensure Compliance: They can help you avoid costly errors, audits, and penalties by ensuring all filings are accurate and compliant with IRS regulations.
- Handle Complex Situations: If you own a business, have international income, or deal with other complex financial scenarios, a professional’s expertise is invaluable.
Don’t wait until tax season to start thinking about your 2026 Tax Savings. Begin discussions with your tax advisor now to implement strategies throughout the year. Proactive planning, informed decision-making, and expert guidance are your best allies in navigating the upcoming tax season successfully.
Conclusion: Your Roadmap to Significant 2026 Tax Savings
The journey to maximizing your 2026 Tax Savings is a continuous process of learning, planning, and adapting. As we’ve explored, the upcoming tax year presents both challenges and significant opportunities, particularly with the potential expiration of key TCJA provisions and the introduction of new legislation. By understanding the anticipated IRS updates, strategically leveraging available deductions and credits, and making informed financial decisions throughout the year, you can significantly reduce your tax liability.
Remember to:
- Stay informed about potential changes to individual income tax rates and standard deductions.
- Meticulously track all expenses that could qualify for itemized or above-the-line deductions.
- For business owners, diligently record all ordinary and necessary business expenses and explore capital expenditure strategies.
- Maximize contributions to retirement accounts like IRAs and 401(k)s for immediate tax benefits.
- Explore education tax credits and student loan interest deductions if applicable.
- Investigate various tax credits, from child-related benefits to energy efficiency incentives.
- Consider advanced strategies like tax loss harvesting and tax-efficient investing.
- Most importantly, consult with a qualified tax professional to tailor a plan specific to your unique financial situation.
Proactive tax planning is not merely about compliance; it’s about empowering your financial future. By starting now and implementing these strategies, you are well-positioned to unlock substantial 2026 Tax Savings and build a more secure financial foundation for yourself or your business. The time to plan for 2026 is now, ensuring you are prepared for whatever the next tax season brings.