Mastering Your Portfolio: Navigating 2026 Fed Rate Hikes
Anúncios
Mastering Your Portfolio: Navigating 2026 Fed Rate Hikes
The financial world is a dynamic landscape, constantly shaped by a myriad of factors, with central bank policies often acting as the primary sculptor. As investors, we are perpetually looking ahead, attempting to anticipate the next significant shift that could impact our portfolios. One such shift that is beginning to capture considerable attention is the potential for Fed Rate Hikes 2026. While 2026 might seem a distant future, the prudent investor understands that strategic planning requires foresight, especially when it comes to monetary policy.
Anúncios
The Federal Reserve’s decisions on interest rates ripple through every corner of the economy, affecting everything from mortgage rates and corporate borrowing costs to the valuation of stocks and bonds. Understanding the potential trajectory of these rates, particularly the anticipated Fed Rate Hikes 2026, is not merely an academic exercise; it is a critical component of building a resilient and profitable investment portfolio. This comprehensive guide will delve deep into the implications of these potential hikes, offering actionable strategies to help you adjust your portfolio now, mitigating risks and seizing emerging opportunities.
Understanding the Fed’s Role and the Rationale Behind Rate Hikes
Before we can effectively prepare for the Fed Rate Hikes 2026, it’s crucial to grasp the Federal Reserve’s mandate and the economic conditions that typically prompt it to raise interest rates. The Fed has a dual mandate: to achieve maximum employment and maintain stable prices. When inflation begins to accelerate beyond comfortable levels, or when the economy shows signs of overheating, the Fed often resorts to increasing the federal funds rate.
Anúncios
Raising interest rates is essentially a cooling mechanism for the economy. Higher rates make borrowing more expensive for businesses and consumers, which can slow down spending and investment, thereby curbing inflationary pressures. Conversely, lower rates stimulate economic activity. The market’s anticipation of Fed Rate Hikes 2026 is often based on current economic trends, inflation data, employment figures, and global economic outlooks. Analysts are already starting to model various scenarios for the coming years, and a consensus is gradually forming around the likelihood of gradual but significant rate adjustments.
The process isn’t always straightforward. The Fed communicates its intentions through forward guidance, minutes from Federal Open Market Committee (FOMC) meetings, and speeches by its officials. Astute investors pay close attention to these signals, as they provide valuable clues about the potential timing and magnitude of future rate changes. Ignoring these signals, especially concerning the potential Fed Rate Hikes 2026, can lead to unexpected portfolio shocks.
The Ripple Effect: How Rate Hikes Impact Different Asset Classes
The prospect of Fed Rate Hikes 2026 has distinct implications for various asset classes. A rising interest rate environment typically leads to a re-evaluation of investment attractiveness across the board. Understanding these impacts is the first step in formulating an effective portfolio adjustment strategy.
Bonds: A Direct Impact
Bonds are perhaps the most directly affected asset class by rising interest rates. When interest rates go up, newly issued bonds offer higher yields, making older bonds with lower yields less attractive. This causes the market value of existing bonds to fall. This inverse relationship is a fundamental principle in fixed-income investing. For investors holding long-duration bonds, the impact of Fed Rate Hikes 2026 could be particularly pronounced. Shorter-duration bonds, while still affected, tend to be less sensitive to interest rate fluctuations.
Consider the yield curve as well. A flattening or inverting yield curve can signal market expectations of economic slowdowns or even recessions, which can further complicate bond investment strategies. Diversifying bond holdings across different durations and credit qualities, or exploring inflation-protected securities (TIPS), can be crucial when anticipating Fed Rate Hikes 2026.
Equities: A Mixed Bag
The impact of Fed Rate Hikes 2026 on the stock market is more nuanced. On one hand, higher borrowing costs for corporations can reduce profitability, potentially leading to lower stock valuations. Growth stocks, which often rely heavily on future earnings projections and access to cheap capital for expansion, can be particularly vulnerable. Their valuations are often discounted back at higher rates, making their future earnings less valuable in present terms.
On the other hand, some sectors might benefit. Financial institutions, for example, often see their net interest margins improve in a rising rate environment, as they can charge more for loans. Value stocks, which are often less reliant on rapid growth and have more stable earnings, might also perform relatively better. Companies with strong balance sheets, low debt, and robust free cash flow are generally better positioned to weather the storm of Fed Rate Hikes 2026.
It’s also important to differentiate between the initial market reaction and the longer-term impact. Markets often react negatively to the announcement or even the anticipation of rate hikes, but they can adapt over time. The key is to identify companies with pricing power that can pass on higher costs to consumers, and those that are less sensitive to consumer discretionary spending.
Real Estate: Sensitivity to Borrowing Costs
Real estate, both residential and commercial, is highly sensitive to interest rates due to its reliance on financing. Higher mortgage rates can cool down housing markets by making homeownership less affordable, potentially leading to a decrease in demand and property values. Commercial real estate also faces headwinds as borrowing costs for developers and investors increase, potentially impacting new projects and property valuations.
However, specific segments of the real estate market might fare differently. Real Estate Investment Trusts (REITs) can be a mixed bag. Those with long-term leases and strong tenants might be more resilient, while those in struggling sectors or with high debt loads could face challenges. Diversification within real estate, potentially through publicly traded REITs or private real estate funds, and a focus on essential services or high-demand areas, could be prudent in the face of Fed Rate Hikes 2026.
Alternatives and Commodities: Potential Hedges
Alternative investments, such as commodities (gold, oil, industrial metals) and hedge funds, can sometimes act as hedges against inflation and market volatility during periods of rising rates. Gold, for instance, is often seen as a safe-haven asset during economic uncertainty and inflationary pressures, although its performance can be complex in a rising rate environment if real rates turn positive. Certain commodities might benefit from increased demand stemming from global economic growth, even with higher rates.
Private equity and venture capital can also offer diversification, though their illiquidity means they are not suitable for all investors. Their performance is often less correlated with public markets, which can be advantageous during periods of interest rate volatility. Exploring these options, carefully considering their risk profiles, could be part of a robust strategy for the Fed Rate Hikes 2026.
Key Strategies for Adjusting Your Portfolio Now
Given the potential for Fed Rate Hikes 2026, proactive portfolio adjustments are not just advisable but essential. Here are several strategic approaches to consider:
1. Re-evaluate Your Asset Allocation
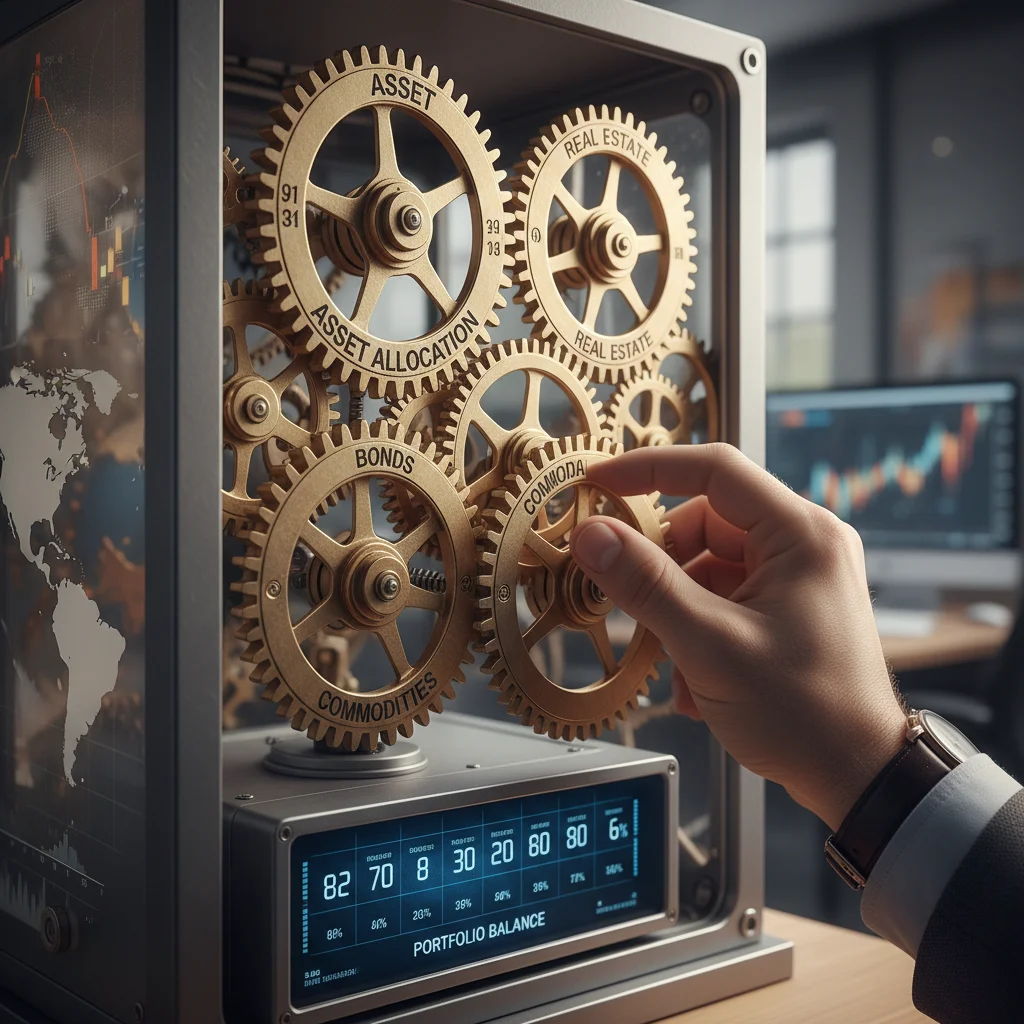
The cornerstone of any investment strategy is asset allocation. With the prospect of Fed Rate Hikes 2026, it’s time to critically review your current mix of stocks, bonds, and other assets. If your portfolio is heavily weighted towards long-duration bonds or growth stocks that are highly sensitive to interest rates, you might consider rebalancing.
- Reduce Bond Duration: Shift from long-term bonds to shorter-term bonds or bond funds. This minimizes interest rate risk, as shorter-duration bonds experience smaller price declines when rates rise.
- Consider Floating-Rate Securities: Investments like floating-rate notes or bank loans have interest payments that adjust with market rates, making them less susceptible to interest rate risk and potentially offering higher yields as rates climb.
- Increase Exposure to Value Stocks and Financials: As mentioned, these sectors tend to perform better in a rising rate environment. Financial institutions benefit from wider net interest margins, while value stocks are often more mature companies with stable cash flows, less reliant on cheap debt for growth.
- Examine Dividend Stocks: While some high-yielding dividend stocks might face pressure if bond yields become more attractive, quality dividend growers with strong fundamentals can still provide income and some capital appreciation. Focus on companies with sustainable dividend policies and robust earnings growth that can support future payouts.
2. Focus on Quality and Strong Fundamentals
In an environment of rising rates and potential economic slowdowns, quality becomes paramount. Companies with strong balance sheets, low debt-to-equity ratios, consistent profitability, and robust cash flow generation are better equipped to navigate higher borrowing costs and potentially slower economic growth.
- Companies with Pricing Power: Seek out businesses that can pass on higher costs to consumers without significantly impacting demand. These are often companies with strong brands, essential products, or services with limited competition.
- Low Debt Levels: Companies with manageable debt loads will be less burdened by rising interest payments, preserving more capital for growth or shareholder returns.
- Strong Free Cash Flow: Businesses that generate significant free cash flow have the flexibility to repay debt, invest in growth, or return capital to shareholders, making them more resilient during economic shifts.
3. Explore Inflation Hedges and Real Assets
If the Fed is raising rates to combat inflation, it makes sense to include assets in your portfolio that historically perform well during inflationary periods. The Fed Rate Hikes 2026 could coincide with persistent inflationary pressures, making these hedges particularly valuable.
- Commodities: Raw materials like oil, natural gas, and industrial metals often see their prices rise with inflation. Gold can also act as a store of value, though its performance can be volatile.
- Real Estate (Strategic): While overall real estate might cool, certain segments, particularly those with inflation-linked leases or in high-growth areas, can still perform well. Consider real estate funds or REITs focused on these niches.
- Treasury Inflation-Protected Securities (TIPS): These government bonds are designed to protect investors from inflation, as their principal value adjusts with the Consumer Price Index (CPI).
4. Consider International Diversification
The Federal Reserve’s actions primarily affect the U.S. economy. While global markets are interconnected, other central banks might be on different monetary policy paths. Diversifying internationally can help mitigate the impact of specific domestic monetary tightening.
- Emerging Markets: Some emerging markets might offer higher growth potential and different interest rate cycles, though they come with their own set of risks, including currency fluctuations and political instability.
- Developed Markets: European or Asian markets might have different economic conditions and central bank policies, offering diversification benefits.
5. Maintain Liquidity and Emergency Funds
In times of economic uncertainty and rising rates, maintaining adequate liquidity is more important than ever. An emergency fund, typically 3-6 months’ worth of living expenses in a high-yield savings account, provides a buffer against unforeseen expenses without forcing you to sell investments at an inopportune time.
Additionally, having some cash on hand allows you to capitalize on potential buying opportunities that may arise if markets experience downturns due to the Fed Rate Hikes 2026. This dry powder can be a significant advantage.
Potential Opportunities in a Rising Rate Environment
While the focus often gravitates towards mitigating risks, the Fed Rate Hikes 2026 also present unique opportunities for astute investors:
Higher Yields on Savings and Fixed Income
For savers, rising interest rates are generally good news. High-yield savings accounts, Certificates of Deposit (CDs), and money market funds will likely offer more attractive returns. This makes it easier to grow your cash reserves and generate income from less risky assets.
Attractive Valuations in Overlooked Sectors
Growth stocks, particularly those with high valuations, might face significant headwinds. However, this could lead to a rotation into more value-oriented sectors that have been overlooked during periods of ultra-low interest rates. Investors willing to do their homework might find compelling opportunities in industries that benefit from a stronger economy or have resilient business models.
Innovation and Disruption
Even in a higher interest rate environment, innovation doesn’t stop. Companies that are genuinely disruptive, solving real-world problems with superior technology or business models, can continue to thrive. The key is to identify those with sustainable competitive advantages and strong management teams, rather than simply chasing speculative growth.
Active Management Advantage
In passive markets, indexing often outperforms. However, during periods of significant economic and monetary policy shifts, active management can shine. Skilled fund managers can adapt more quickly to changing conditions, identifying undervalued assets and avoiding overvalued ones, potentially outperforming broad market indices. This is particularly relevant when navigating the complexities of Fed Rate Hikes 2026.
Monitoring Economic Indicators and Staying Informed
Successfully navigating the potential Fed Rate Hikes 2026 requires continuous monitoring of economic indicators and staying informed about central bank communications. Key indicators to watch include:
- Inflation Data: Consumer Price Index (CPI), Producer Price Index (PPI), and Personal Consumption Expenditures (PCE) are crucial for understanding inflationary pressures.
- Employment Statistics: Non-farm payrolls, unemployment rate, and wage growth provide insights into the health of the labor market.
- GDP Growth: Gross Domestic Product figures indicate the overall economic expansion or contraction.
- Consumer Confidence: Surveys on consumer sentiment can signal future spending trends.
- Manufacturing and Services PMIs: Purchasing Managers’ Indexes offer a snapshot of economic activity in key sectors.
Regularly reviewing the Federal Reserve’s statements, FOMC minutes, and speeches by Fed officials will provide invaluable context and guidance regarding their policy intentions. Subscribing to reputable financial news sources and consulting with financial advisors are also vital components of an informed investment strategy.
Conclusion: Proactive Planning for a Resilient Portfolio
The anticipation of Fed Rate Hikes 2026 is a significant factor that demands attention from every investor. While no one can predict the future with absolute certainty, understanding the potential impacts and proactively adjusting your investment portfolio can make a substantial difference in its resilience and performance. By re-evaluating asset allocation, focusing on quality companies, exploring inflation hedges, diversifying internationally, and maintaining liquidity, you can position your portfolio to not only withstand potential headwinds but also capitalize on emerging opportunities.
Remember, investing is a marathon, not a sprint. The key is to have a robust, well-thought-out strategy that can adapt to changing economic climates. The Fed Rate Hikes 2026 are not a reason for panic, but rather an invitation for strategic review and intelligent repositioning. By taking these steps now, you can build a more resilient portfolio, better prepared to navigate the complexities of the future economic landscape and achieve your long-term financial goals.
Consulting with a qualified financial advisor can provide personalized guidance tailored to your specific financial situation, risk tolerance, and investment objectives. Their expertise can be invaluable in translating these broad strategies into concrete actions for your portfolio.